U.S. spot Bitcoin ETF net flows turned negative on the most recent reporting day, with the aggregate across all listed products recording $33.88 million in net outflows, meaning redemption pr
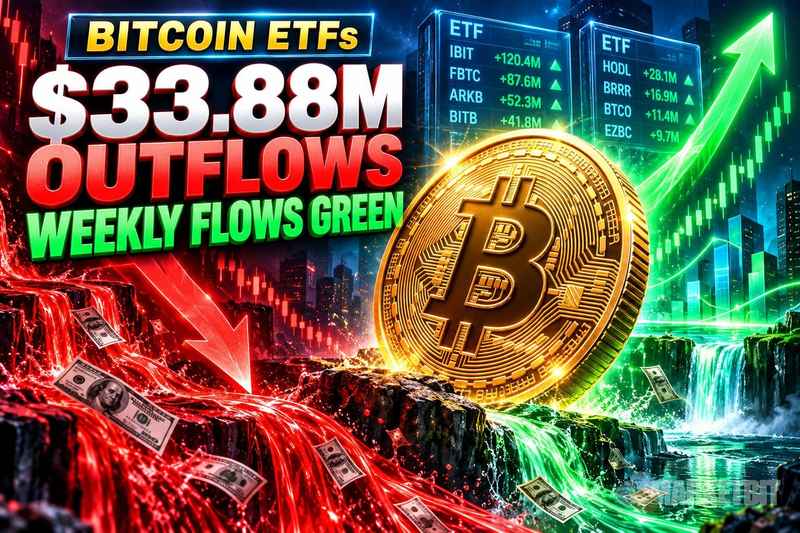
U.S. spot Bitcoin ETF net flows turned negative on the most recent reporting day, with the aggregate across all listed products recording $33.88 million in net outflows, meaning redemption pressure exceeded new capital allocation on that session. The seven-day cumulative net flow reading, however, remained in positive territory, producing a split-signal data environment that warrants precise interpretation rather than directional extrapolation.
What the $33.88 Million Daily Outflow Actually Measures
Net outflow is a precise term: it registers when aggregate redemptions across all U.S. spot Bitcoin ETF products exceed aggregate creations in a single trading session. The $33.88 million figure represents that single-session net, not a rolling average, a monthly total, or a fund-level breakdown. For related coverage, see Swiss Regulator Clears First Retail Bitcoin ETF.
A single negative session does not structurally alter the flow picture. ETF capital movement is episodic by nature; institutional rebalancing, options expiry cycles, and short-duration hedging programs all generate one-day redemption spikes that reverse within the same week.
FLOW SNAPSHOT
- Daily net flow: -$33.88 million (net outflow)
- Seven-day net flow: Positive (exact total not confirmed)
- Time-frame contrast: Single-session negative vs. rolling-week positive
The split between a negative daily print and a positive seven-day cumulative is the key structural fact here. Earlier sessions inside the same rolling week absorbed enough net creation volume to keep the aggregate above zero, absorbing the most recent day's redemption pressure without flipping the weekly total negative.
Why the Seven-Day Window Remains Positive After a Down Session
Rolling seven-day flow totals aggregate every individual daily net reading from the prior six sessions plus the current one. A single session of $33.88 million in net outflows only flips the weekly total negative if the cumulative surplus from the preceding six days was smaller than $33.88 million. In this case, it was not, so the weekly aggregate held positive.
This arithmetic is directly relevant to how to weight the daily data point. If the seven-day surplus before the outflow session was, for example, several hundred million dollars, then a sub-$34 million single-day redemption is a minor offset, not a directional shift. Without confirmation of the precise seven-day total, that exact magnitude cannot be stated, but the sign — positive — is the reported outcome.
The gap between short-period and rolling-period flow data is a standard feature of any product that sees institutional-scale allocation. BlackRock's iShares Bitcoin ETF recorded $1.41 billion in net outflows in a single month in May, illustrating that even the largest product can run extended redemption cycles without necessarily signaling a permanent structural exit. Daily readings are noisier than weekly or monthly aggregates by design.
Reading the Divergence: What Each Time Frame Signals
Daily ETF flow data carries the highest noise-to-signal ratio of any standard reporting window. Authorized participant activity, basis trade unwinds, and end-of-day rebalancing by multi-asset funds all produce single-session spikes in either direction that normalize within the week.
The seven-day reading provides a cleaner signal because it smooths over at least one full week of institutional settlement cycles. A positive seven-day total indicates that, net of all creation and redemption activity over that window, more capital entered than exited the collective U.S. spot Bitcoin ETF structure. That reading has more interpretive weight than a single negative session.
The relevant monitoring question going forward is whether daily outflows persist across multiple consecutive sessions. One session of $33.88 million in net outflows against a positive seven-day backdrop is a data point, not a pattern. Three or more consecutive negative sessions would begin to erode the seven-day total and produce a more informative directional read. Until that sequence either confirms or fails to materialize, the two readings together describe a mixed but not structurally broken flow environment.
Product innovation in the Bitcoin ETF space continues to expand the range of capital that can access the wrapper. BlackRock filed for a Bitcoin ETF with downside protection features, and separately filed for an iShares Bitcoin Managed Protect ETF with the SEC, both of which could attract allocation profiles that behave differently from plain-vanilla spot exposure. Structural product diversification within the Bitcoin ETF category means future flow readings will increasingly blend signals from different investor types.
What to Monitor in the Next Reporting Cycle
Three metrics will clarify whether the $33.88 million outflow session was an isolated reading or the start of a sustained redemption trend.
First, the persistence of daily outflows: if the next one to three sessions also print net negative, the seven-day cumulative will contract and may turn negative, providing a more definitive signal than the current split reading.
Second, the magnitude ratio between the daily and the seven-day total: a narrow positive weekly surplus relative to the daily outflow indicates limited buffer. A wide surplus indicates the single-session redemption has minimal impact on the rolling picture.
Third, the directional consistency across multiple ETF products: a market-wide redemption event affects all authorized participants simultaneously and produces correlated outflows across products. A single-product event may reflect fund-specific activity rather than aggregate demand shifts. The current report covers the aggregate total; product-level decomposition was not available in the reported data.
ETF flow data and Bitcoin spot price direction are distinct series. Capital entering or exiting the ETF wrapper does not mechanically determine spot price; it reflects investor demand for regulated exposure, not total market demand for the underlying asset. Prior analysis of Bitcoin at the $82,500 level examined how Wintermute, Fed positioning, and BlackRock IBIT protection interacted, illustrating that spot price dynamics involve a broader set of variables than ETF-wrapper flows alone.
The $33.88 million daily outflow sits below the threshold that historically moved the seven-day aggregate into negative territory during prior redemption cycles. The positive seven-day reading, as reported, confirms that prior-week inflows provided sufficient cushion. The next two to three trading sessions are the decisive data window: sustained outflows would compress that cushion; a return to net inflows would reinforce the positive weekly trend and reduce the significance of the single negative session to statistical noise.
Additional source references: source document 1, source document 2.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Cryptocurrency and digital asset markets carry significant risk. Always do your own research before making decisions.
Read original article on marketbit.net