For decades, the unspoken rule in corporate finance has been simple. You do not give software the keys to the company vault. Automation is welcome to organise receipts, classify ledgers, and
For decades, the unspoken rule in corporate finance has been simple. You do not give software the keys to the company vault. Automation is welcome to organise receipts, classify ledgers, and build charts, but when money actually moves, a human must sign the check. The anxiety around autonomous software is entirely justified. Software asks confidently, acts instantaneously, and lacks the anxiety that prevents a junior analyst from accidentally draining an account.
Today, Bujeti, the Y Combinator-backed Nigerian financial operating system, is launching a major product that tests the boundaries of this rule. The company is introducing agentic AI natively into its platform. The product, called BRAIN (Bujeti’s Real-time Agent Intelligence Network), deploys four distinct AI agents to handle document capture, invoice collections, transaction monitoring, and internal policy queries. Crucially, the company insists these agents will not be able to authorise payments.
Bujeti CEO and co-founder Cossi Achille Arouko insists the development is not a mere feature update but an inevitable shift in how African businesses govern capital. He argues that the continent’s fintech progression has moved from consumer payments in its first decade to business payments in its second. The third decade, Arouko insists, belongs to intelligence.
The strategy rests on a core belief about where AI delivers value in B2B finance. Over the past three years, Bujeti built a sprawling financial operating system. Founded in 2022 by Arouko and Samy Chiba, Bujeti initially explored diaspora remittances before pivoting to corporate expense governance in 2023. After raising a $2 million seed round led by Y Combinator, Entrée Capital, Voltron Capital, Kima Ventures, and Arash Ferdowsi, the team systematically expanded its software footprint.
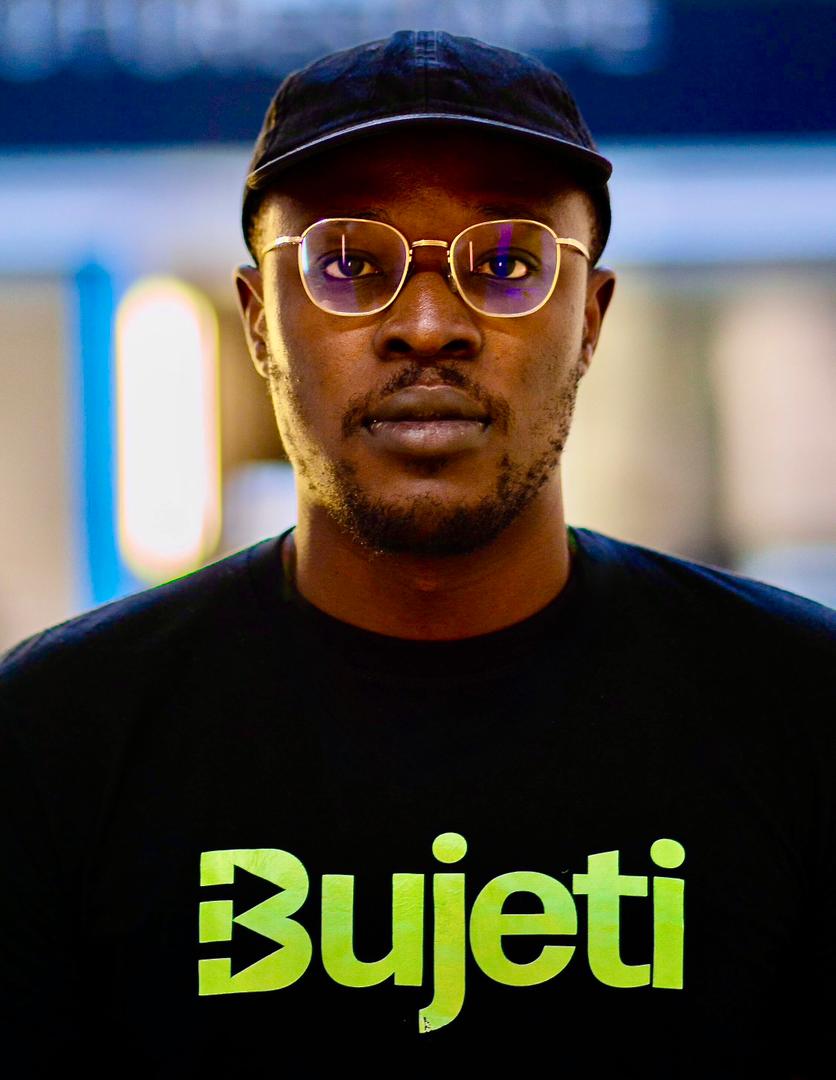
Cossi Achille Arouko, founder and CEO of Bujeti
Today, the platform serves over 1,000 corporate teams across its primary markets of Nigeria and Kenya, managing multi-currency operations across naira, shillings, and US dollars, with an expansion into Francophone Africa underway. Bujeti reports that its platform helped its clients save N1.25 million in annual savings per employee alongside a 54 per cent increase in team productivity. The company also cites benchmarking studies by PwC indicating that finance analysts spend forty per cent of their day gathering data rather than analysing it.
“We did not add products,” Arouko states. “We kept following the money until it was brutally transparent for businesses.”
How Bujeti’s agentic AI, BRAIN, works
Because Bujeti already owns the financial record, its new AI layer does not have to pull context through frail third-party integrations. It reads the books natively.Instead of deploying a single conversational bot tasked with fielding open-ended prompts, Bujeti split the workload into four domain-specific systems termed “AI Teammates”:
- Fetch: Connects to inboxes, cloud storage, and accounting software to extract and categorise invoices, receipts, and bank statements, pushing uncertain extractions to human queues.
- Chaser: Manages accounts receivable across WhatsApp, SMS, and email, actively chasing outstanding invoices and proposing payment plans when clients face liquidity shortfalls.
- Watchdog: Operates as a continuous internal audit layer, running daily checks on transactions and contracts while flagging suspicious line items and auto-renewals.
- Concierge: Serves as a policy navigator, parsing company handbooks to answer staff expenditure queries with explicit citations, configured to decline answering when data is missing.
The central tension in agentic AI remains the question of autonomy versus liability. A rogue chatbot that hallucinates a customer service reply is embarrassing. A rogue finance agent that pays a fraudulent vendor is catastrophic. Arouko points out that high-profile AI failures occur when models are given standing write access to production environments without a gate on irreversible actions.
“The agent, by design, does not decide what it is allowed to do,” Arouko notes. “Permission does not live in the prompt. It lives in the system, outside the model, in scoped credentials the model cannot reason its way past. A limit an agent can be talked out of is not a limit.”
Bujeti enforces a strict taxonomy based on whether an action is reversible or irreversible. Reversible work, like classifying a transaction or drafting a reminder, proceeds autonomously. Any irreversible action, or anything that touches money, becomes a proposal that a human must commit. Furthermore, anything falling below a defined confidence threshold is escalated to a human queue.

Building agentic AI for Lagos is materially different from building it for London. The unit economics of replacing human attention with machine processing must make sense in naira. Arouko explains that running an agent across every transaction daily has to cost less than the attention it replaces. He maintains that agentic finance in Africa was never a capability question, but rather a unit economics question that is only now becoming viable.
Looking ahead, Bujeti also announced a forthcoming secure doorway, the Bujeti MCP, allowing external AI tools like ChatGPT or Claude to securely query a business’s live ledger with strict permissions.
The underlying bet is clear. Whoever builds the most robust, well-categorised ledger will inevitably own the intelligence layer that sits on top of it. By focusing first on the unglamorous plumbing of business payments across volatile currencies, Bujeti has engineered a system where the AI simply reads the reality the software has already built. The real test is whether African businesses are ready to let machines draft the proposals, even if humans keep a firm grip on the wallet.