Cardano Lending and Borrowing Platforms Explained Through DeFi Markets Cardano lending and borrowing platforms are decentralized finance apps where users deposit crypto to earn interest or lo
Cardano lending and borrowing platforms are decentralized finance apps where users deposit crypto to earn interest or lock it as collateral for a loan.
Smart contracts on the Cardano blockchain enforce the rules, so no bank approves each request.
Interest in Cardano-lending-and-borrowing-platforms comes from a practical problem. Holders often need stablecoins or cash but prefer not to sell ADA, and a crypto-backed loan offers one route, with risks attached.
The official Cardano app catalogue uses a lending tag for projects that provide lending and borrowing of ADA. Cardano-lending-and-borrowing-platforms under that tag work like on-chain money markets. Lenders supply tokens, borrowers post collateral, and code tracks balances, interest, and repayment.
Collateral is an asset that a borrower locks to secure a loan. If the borrower stops repaying, or the collateral loses too much value, the protocol can sell it to cover the debt.
Most DeFi loans are over-collateralized, meaning the collateral is worth more than the amount borrowed. As an illustration, a borrower might lock assets worth $150 to borrow $100 in stablecoins. That cushion protects lenders when prices fall.
How Do DeFi Loans Work on Cardano?
The flow looks similar across most Cardano-lending-and-borrowing-platforms, although each app sets its own limits and fees. The list below shows the general order.
Connect a wallet. A Cardano-wallet signs each transaction, so no company account is needed.
Supply collateral. The user deposits ADA or another supported token into the protocol.
Borrow. The app allows borrowing up to a set share of the collateral value, called the loan-to-value ratio.
Pay interest. In pooled markets, where lenders share one liquidity pool, rates usually move with supply and demand.
Repay and withdraw. Once the debt is cleared, the collateral-is released.
Liquidation is the step that borrowers on Cardano-lending-and-borrowing-platforms watch most closely. It happens when collateral-value drops far enough that the loan becomes unsafe, and the protocol sells part of the-collateral to repay lenders.
Borrowers who use ADA as-collateral need to follow price levels, and anADA price forecast can help frame the risk. No forecast is reliable, so a safety buffer matters more than a prediction.
Why Does Cardano's Design Matter for Lending?
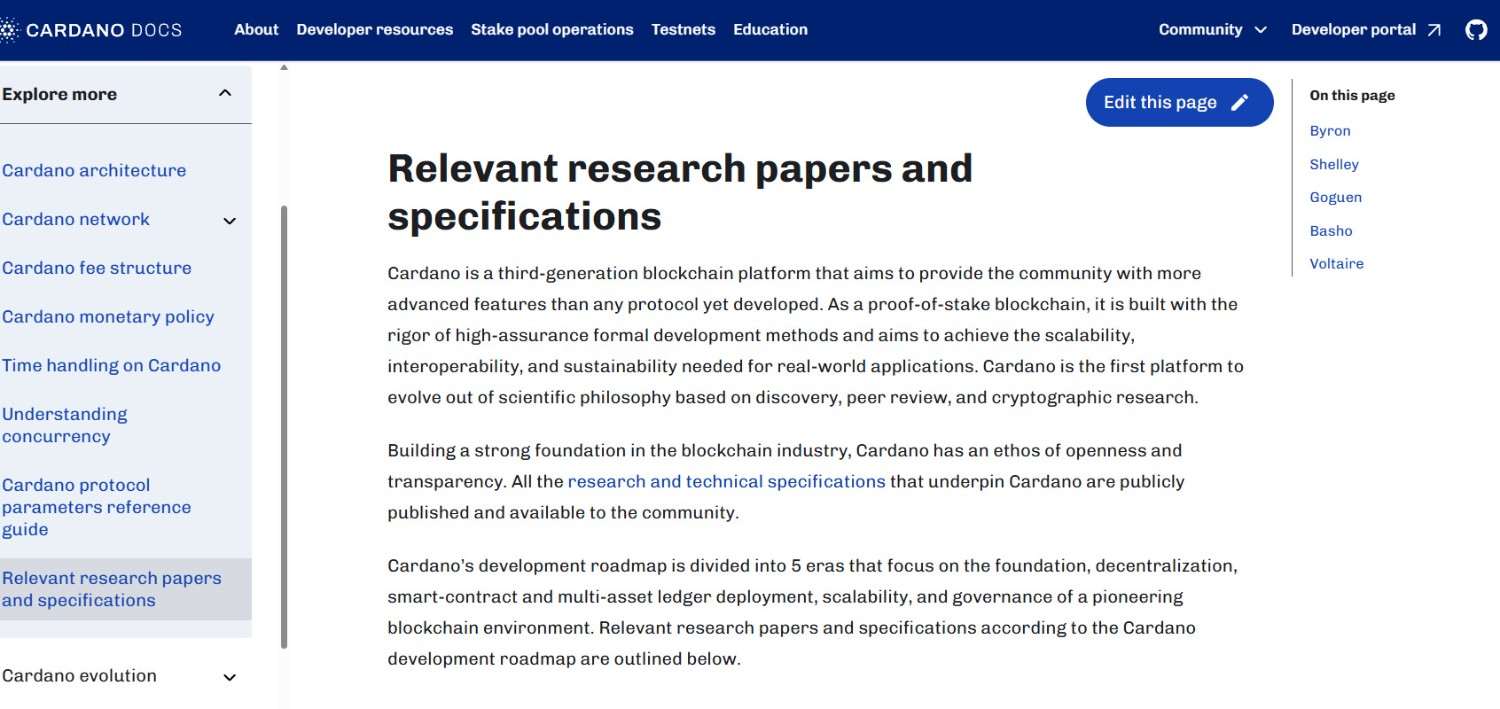
Cardano-uses the Extended UTXO model, where value is tracked as separate unspent outputs instead of one account balance. The official documentation lists a research paper on this model, plus work on native multi-asset support and the Marlowe language for financial contracts.
The same documentation lists research on Djed, a crypto-backed stablecoin design. It does not say that any specific lending-app is built on these papers, so that link should not be assumed. The full list sits in therelevant research papers section of the Cardano docs.
Analyst view: predictable transaction behavior may help builders reason about contract outcomes, which matters when-collateral is involved. That is an interpretation, not a confirmed advantage for any single Cardano DeFi protocol.
The official catalogue lists several lending-apps, with snapshots dated 8 October 2026. The table covers Cardano-lending and-borrowing platforms from that list, using the descriptions and transaction counts shown.
Platform
Official description
On-chain transactions (30 days)
Dano Finance
Lending-borrowing, and trading with cross-pool collateral and unified interest rate markets
42,869
Liqwid
Non-custodial pooled-lending with liquid staking and qToken collateral receipts
3,308
FluidTokens
Cardano-Bitcoin protocol for lending, borrowing, staking, rentals, and boosted stake
Not shown
Dano Finance shows the highest count in this set. Its entry describes an all-in-one platform with cross-pool collateral, which suggests collateral in one market may support borrowing in another. Exact mechanics need checking in the project's documentation.
A transaction count is not the same as total value locked or loan volume. High activity shows usage but says little about deposit size or safety. An open-source tag also means the code can be inspected, not that it has been audited.
What Are the Main Risks to Consider?
Even well-used Cardano-lending-and borrowing platforms carry layered risks.
Liquidation risk: A sharp ADA drop can trigger forced sales of collateral.
Smart contract risk: Bugs can cause losses, and an audit lowers that risk without removing it.
Price feed risk: A faulty price feed can cause unfair liquidations.
Liquidity risk: If a pool runs short of funds, withdrawals may be delayed.
Stablecoin risk: Borrowed stablecoins can lose their peg to the dollar.
Scam risk: Fake apps copy real interfaces, so addresses should be checked against official catalogue links.
Lending-is a core DeFi function, and Cardano already has several active apps, from pooled-lending to Bitcoin-linked products.
Transaction counts for most listed apps remain modest, and ADA-collateral can swing sharply. The latest October 2026 ADA outlook shows how quickly market conditions can change.
Falling collateral-prices push loans closer to liquidation. The ADA recovery targets analysis covers the price zones that traders are tracking.
Overall, Cardano lending and borrowing platforms look like a developing part of the ecosystem. Outcomes depend on user growth, security records, and market conditions, none of which can be predicted.
Cardano lending-and borrowing platforms let users earn interest or borrow against-collateral through smart contracts. Dano Finance, Liqwid, and FluidTokens show different designs, from all-in-one markets to pooled-lending and Bitcoin-linked products.
What remains uncertain is long-term safety, real loan volume, and behavior in a sharp market drop. Documentation, audit reports, liquidation rules, and collateral-ratios are the next things to check.
Disclaimer:
This article is for education only and is not financial or investment advice. Crypto lending can cause partial or total loss of funds. Research each platform independently before deciding.