The Commodity Futures Trading Commission is pressing forward with a standalone crypto oversight framework, an effort that could bring meaningful clarity to digital asset markets within the CF
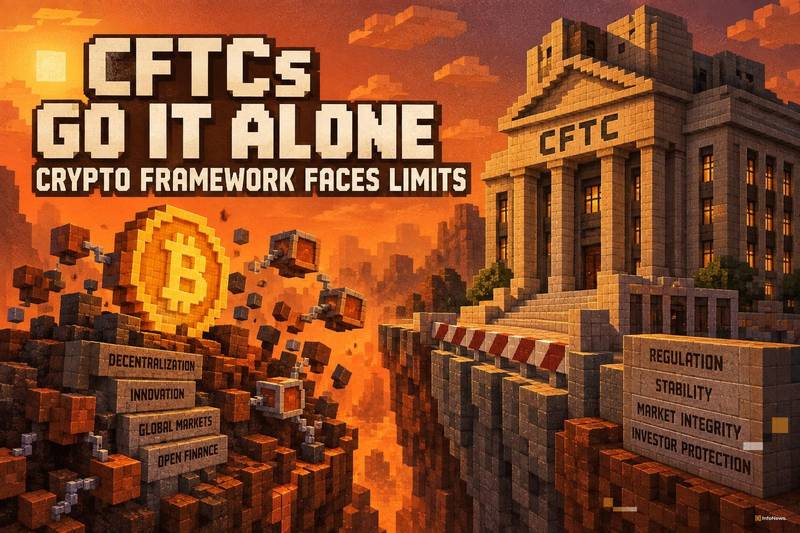
The Commodity Futures Trading Commission is pressing forward with a standalone crypto oversight framework, an effort that could bring meaningful clarity to digital asset markets within the CFTC's jurisdiction, but one that faces structural limits without broader interagency alignment or congressional action.
The case for a standalone CFTC approach
The CFTC has jurisdiction over commodity derivatives and certain spot commodity markets, a mandate that covers Bitcoin and, in some contexts, other digital assets classified as commodities. A dedicated CFTC crypto framework would, in principle, give exchanges and market participants a defined rulebook for registration, reporting, and conduct requirements within that remit. For related coverage, see CFTC Moves Ahead With Crypto Rules as CLARITY Act Stalls.
That clarity has practical value. Markets operating under defined federal oversight carry lower counterparty and compliance risk than those operating in a regulatory grey area. For Bitcoin specifically, a settled CFTC framework could reinforce its commodity classification and support deeper institutional participation in derivatives markets.
The CFTC has previously moved to open rulemaking on retail leveraged crypto markets, signaling that the agency views its existing statutory authority as sufficient to act without waiting for Congress. That posture underpins the go-it-alone approach: proceed with what the agency can do now, rather than wait for comprehensive legislation that has repeatedly stalled.
Where a standalone approach runs into limits
The core constraint is jurisdictional overlap. The Securities and Exchange Commission asserts authority over digital assets it deems securities, and the boundary between a commodity and a security in crypto markets is actively contested. A CFTC framework advancing while the CLARITY Act stalls does not resolve that boundary; it leaves it open to continued litigation and conflicting agency guidance.
Enforcement coverage is a second limit. The CFTC's spot market authority outside of fraud and manipulation is narrower than its derivatives authority. A framework that governs crypto derivatives and futures comprehensively may still leave large portions of spot trading, lending, and staking activity without a clear federal overseer, regardless of how well the CFTC rules are drafted.
Interagency coordination compounds both issues. Even where the CFTC and SEC have moved toward joint crypto regulations, the two agencies operate under different statutory frameworks, different enforcement cultures, and different congressional oversight committees. A unilateral CFTC framework cannot substitute for the kind of unified federal approach that would require either a joint rulemaking or new legislation.
What this means for Bitcoin and crypto markets
For Bitcoin markets, a functioning CFTC framework carries the most direct relevance. Bitcoin's commodity classification is the most settled of any digital asset, and CFTC oversight of Bitcoin derivatives is already established through regulated futures products. Expanded CFTC rules could deepen that market and reduce uncertainty for institutional counterparties.
For broader crypto markets, the go-it-alone approach offers partial coverage at best. Assets that may be securities fall outside CFTC reach, and the framework does not address the full stack of activities, from token issuance to secondary market trading, that define how most participants interact with digital assets today.
The CFTC has moved further than many expected given the legislative stall, as seen in its proposal to bring crypto exchanges under federal oversight. But the limits of acting without congressional authorization or a negotiated interagency boundary remain real. A standalone framework can establish clear rules within the CFTC's lane; it cannot widen that lane unilaterally.
Until Congress draws a definitive jurisdictional line between the CFTC and SEC, or the two agencies reach a durable coordination agreement, any CFTC-only framework will be comprehensive within its scope and incomplete at its edges. For Bitcoin, that scope is relatively well-defined. For the rest of digital asset markets, the gaps matter as much as the rules themselves.
Additional source references: source document 1, source document 2.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Cryptocurrency and digital asset markets carry significant risk. Always do your own research before making decisions.
Bitcoininfonews first published the article titled CFTC's Go-It-Alone Crypto Framework Faces Limits.