Crypto lending spent most of its history asking borrowers to accept one uncomfortable variable: the interest rate could change while the loan was still open. Coinbase has now added a differen
Crypto lending spent most of its history asking borrowers to accept one uncomfortable variable: the interest rate could change while the loan was still open.
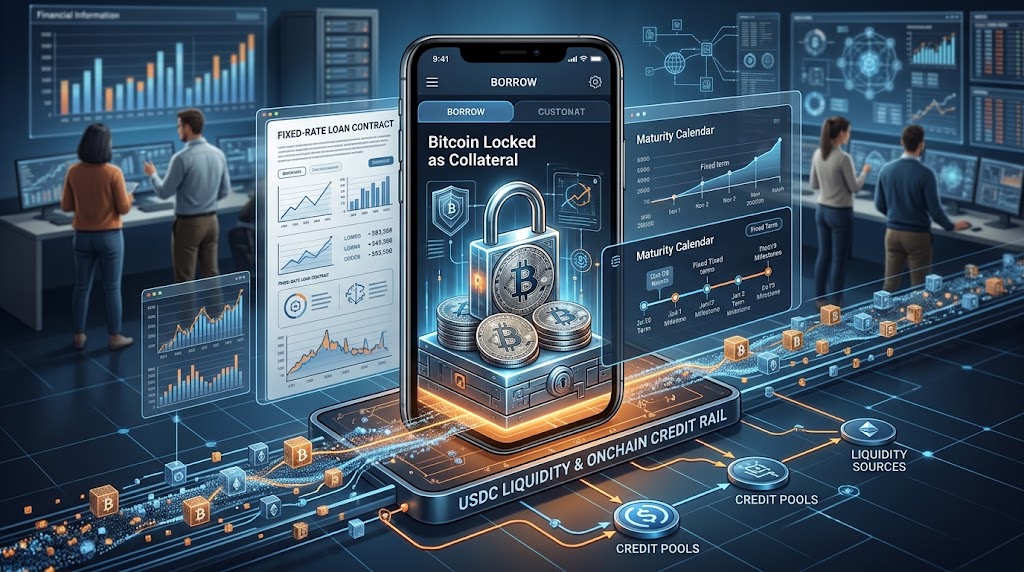
Coinbase has now added a different option. Users can borrow USDC against bitcoin at a fixed rate with a fixed repayment date, using Morpho Midnight on Base. The rate and maturity are set when the loan is opened rather than floating with utilization afterward.
That sounds like a product update. Structurally, it is a much bigger change. One of DeFi credit's most unfamiliar features is being replaced with the same basic promise traditional borrowers already understand: this is what the money costs, and this is when it is due.
Morpho describes the launch as the first enterprise-scale integration of Midnight, its fixed-rate, fixed-term credit protocol. Coinbase owns the customer interface, Morpho supplies the lending market, and settlement occurs on Base.
The split matters because it is another example of decentralized finance disappearing into a mainstream front end. A user does not need to visit a protocol interface, manage a separate lending position or manually source liquidity. The protocol becomes infrastructure underneath a familiar app.
Coinbase already offers variable-rate loans through Morpho. According to Morpho, those loans have grown to more than $1.4 billion in active borrowing backed by approximately $3 billion of collateral. Fixed-term credit is being added to an existing lending business rather than tested as a small standalone experiment.
The new structure removes interest-rate uncertainty. It does not remove collateral risk.
A borrower still posts volatile crypto against a dollar-denominated liability. If the value of that collateral falls far enough relative to the loan, liquidation remains possible. Coinbase also states that a fixed-rate loan can become eligible for liquidation if it is not repaid by maturity even when its loan-to-value ratio would otherwise be healthy.
That second trigger is easy to miss. Variable-rate crypto loans are usually discussed as price-risk products. Fixed-term loans add calendar risk. The borrower now has two things to manage: the value of the collateral and the date on which the debt must be cleared.
Optimisus covered the same underlying trade in Borrowing Against Crypto Keeps Your Upside. Here Is What It Actually Costs. Borrowing avoids a sale, but it converts an unleveraged crypto position into a leveraged one. A predictable rate changes the financing. It does not change that arithmetic.
Traditional credit markets revolve around term. A one-month loan, a one-year loan and a five-year loan are not interchangeable because lenders price time, liquidity and default risk differently. Most onchain lending historically compressed that structure into open-ended pools with variable rates.
Morpho Midnight is trying to introduce a real maturity dimension. Coinbase currently offers short maturities around month-end, but the architecture matters more than the initial menu. Once rates can be quoted for defined periods, onchain credit can begin to develop something closer to a term structure instead of a single utilization-driven rate.
That is useful for institutions, fintechs and structured products because a known liability can be matched against a known asset duration. It is also one reason Morpho has framed Midnight as infrastructure for more than retail crypto-backed loans.
The direction of travel is worth noticing. Bitcoin is still rarely used to price everyday goods, but it is increasingly used as collateral for dollar liquidity.
MARA borrowed hundreds of millions of dollars against pledged bitcoin this year rather than selling it, a structure Optimisus examined in MARA Pledged 18,750 Bitcoin for $600 Million. The Filing Does Not Say What Price Triggers a Margin Call. Coinbase is bringing a retail version of the same logic into its consumer app.
That is a different adoption path from the one bitcoin was originally sold on. The asset does not have to replace dollars to become financially useful. It can sit underneath dollar credit as collateral.
The next useful numbers are not the number of accounts that click Borrow. They are loan duration, average LTV, liquidation rates, repeat borrowing and whether fixed-rate liquidity remains deep enough when markets become volatile.
A fixed rate only feels bank-like if the market behind it remains available when borrowers actually need it. If spreads widen sharply or maturities disappear during stress, the product is still crypto-native credit with a familiar wrapper.
If liquidity holds, this becomes something else: a consumer financial product whose visible interface is centralized, whose credit engine is decentralized, and whose collateral is bitcoin. That combination is becoming increasingly normal.
This is not financial advice.