Key Highlights The U.S. Senate blocked the Digital Asset Market Clarity Act on September 15, 2026 with a 50–49 vote — falling 10 votes short of the 60 needed to advance, despite the House hav
Key Highlights
- The U.S. Senate blocked the Digital Asset Market Clarity Act on September 15, 2026 with a 50–49 vote — falling 10 votes short of the 60 needed to advance, despite the House having passed it in July 2025.
- The failure leaves SEC vs. CFTC jurisdiction, securities classification, and exchange operating rules unresolved in statute — keeping the legal gray zone intact and replacing congressional law with agency discretion.
- Bitcoin is the least exposed to the ruling's consequences — exchanges, altcoins, DeFi protocols, and stablecoin yield remain in the most uncertain regulatory position.
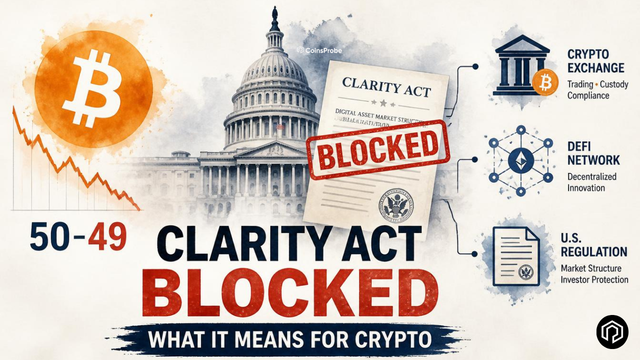
The U.S. Senate voted 50–49 on September 15, 2026 to block the Digital Asset Market Clarity Act — the CLARITY Act — from advancing. The bill needed 60 votes. It got 50. The House had already passed it in July 2025. That bipartisan House vote now sits as a historical footnote rather than a legislative foundation.
This was not a ban on crypto. Trading remains legal. The GENIUS Act still governs payment stablecoins. What died on September 15 was the chance for the United States to have a comprehensive, durable crypto market structure law in 2026 — one that would have settled, in statute, which tokens are securities, which are commodities, how exchanges must operate, and how public officials can deal in digital assets.
 Clarity Act Stalls/Source: @EricLDaugh (X)
Here is what that failure actually means — broken down by consequence.
1. The Legal Gray Zone Continues
The most immediate consequence is the one that was always the most expensive: Congress did not settle who regulates which digital assets.
Bitcoin’s commodity status is the most accepted part of U.S. crypto law — it is relatively insulated from this outcome. Everything else remains contested. Exchanges, token issuers, and DeFi protocols still have no statutory answer to the question “is this token a security or a commodity?” — which means they continue to rely on expensive legal opinions, enforcement precedents, and educated guesses rather than a written rulebook.
That uncertainty is not a minor compliance burden. It is the primary reason institutional capital has been slower to deploy into U.S. crypto infrastructure than the market’s size would otherwise attract — and it remains fully intact after September 15.
2. Agencies Write the Rules Instead of Congress
Without CLARITY, the SEC and CFTC retain the authority to shape crypto policy through guidance documents, proposed rulemakings, and applications of existing statutes — many of which were written before crypto existed.
Both agencies have been active. That can still produce functional rules. But there is a fundamental durability problem: an agency rule can be rewritten when a White House changes or a commission chair is replaced. Repealing an act of Congress requires another act of Congress — a far higher bar.
What the industry loses without CLARITY is not just clarity — it is permanence. The framework that emerges from agency action is inherently political, vulnerable to the next election cycle, and reversible in ways that statutory law is not.
3. The Pain Is Unevenly Distributed
The consequences of the CLARITY Act’s failure are not the same across every part of the market:
SectorRegulatory Exposure Post-FailureBitcoinLowest — commodity status already most accepted in U.S. lawStablecoins (issuance)Covered by GENIUS Act — relatively protectedStablecoin yieldsStill unresolved — a live political fightExchangesHigher compliance costs, slower product launches, more listing riskAltcoinsSecurities classification still contested case-by-caseDeFi protocolsMost exposed — no statutory framework for decentralized structures
The stablecoin yield issue deserves specific attention. The GENIUS Act covers stablecoin issuance and reserve requirements — but CLARITY’s unfinished business included rewards on stablecoin balances. Banks actively opposed language they argued would pull deposits out of the traditional financial system. That fight is now unresolved in statute and will continue through agency channels.
Wall Street analysis before the vote had already projected that a failed market-structure bill would maintain a “risk premium” on U.S. crypto platforms and favor Bitcoin-heavy exposure over regulatory-sensitive tokens. That analysis now applies directly.
4. Market Reaction — Headline Shock, Not Structural Collapse
Bitcoin dropped several percent in the immediate aftermath of the Senate vote. Coinbase and Circle shares fell more sharply than BTC itself — reflecting the market’s assessment that centralized U.S. crypto businesses carry more regulatory exposure than Bitcoin does.
That reaction was a headline shock, not a structural verdict. The market sold the uncertainty repricing — the removal of the probability that durable statutory clarity was arriving in 2026. It was not a market pricing in illegality or shutdown.
Trading remains legal. Banks, asset managers, and crypto firms can still build. What changed on September 15 was the probability of a congressional rulebook arriving before the next election cycle — and the market priced that probability downward immediately.
5. The U.S. Falls Further Behind Jurisdictions With Finished Rulebooks
Europe has MiCA. Multiple other jurisdictions have written, enacted crypto frameworks. The CLARITY Act’s failure extends the period during which the United States — the world’s largest capital market — operates without a comprehensive digital asset law while other major economies do not.
The practical consequence is not that U.S. capital flees to Europe. It is that product design decisions, token launches, and exchange infrastructure investments continue to be partially shaped by regulatory arbitrage — with “will this token be treated as a security next year?” remaining an unresolved question that influences where businesses domicile and where they launch.
The U.S. market does not shut. It continues operating under conditions of regulatory uncertainty that its international competitors are progressively eliminating.
6. Why the Bill Failed — Politics, Not Just Policy
The mechanics of the Senate vote are important context. Democrats blocked the bill primarily on ethics grounds — arguing that CLARITY did not do enough to prevent federal officials, including President Trump, from profiting from crypto businesses. Trump’s family crypto ventures were reported to have generated approximately $1.4 billion during this period.
Republicans offered revised ethics language. It was not sufficient to bring enough Democratic votes across the 60-vote threshold. A small number of Republican senators also voted no — partly reflecting bank industry concerns about stablecoin yield language that banks argued would compete with deposit accounts.
The industry deployed significant lobbying resources to advance CLARITY. That effort now waits for the next Congress. A lame-duck legislative revival is theoretically possible and historically unlikely.
What Did NOT Happen on September 15
Several outcomes that did not occur are worth stating directly to counter misinformation:
- Crypto was not outlawed — trading, custody, and development remain legal
- The GENIUS Act still governs payment stablecoins — stablecoin issuers retain their statutory framework
- Current agency work did not automatically reverse — SEC and CFTC rules and guidance remain in force
- The House vote still stands — bipartisan support for market-structure legislation exists; this Senate package failed, not the concept
Bottom Line
The CLARITY Act’s 50–49 Senate failure means the United States enters the final months of 2026 — and potentially 2027 — without a comprehensive crypto market law. The industry continues operating under agency discretion, court-shaped precedents, and the political weather of each new administration.
Bitcoin can live with that better than most. Its commodity status is the most settled piece of U.S. crypto law and does not require CLARITY to be functional. Exchanges, altcoins, DeFi protocols, and stablecoin yield products live with it significantly worse — their regulatory position remains genuinely uncertain in ways that impose real costs on product development, compliance, and institutional adoption.
The next realistic legislative opportunity is the next Congress — following the midterm elections. Unless something unusual changes the legislative calendar before then, that is the timeline for a second attempt at the comprehensive market-structure law that September 15, 2026 could not deliver.
Disclaimer: This article is for informational purposes only and does not constitute legal or financial advice. Always consult qualified legal and financial professionals for guidance specific to your situation.