On Wednesday, September 16, 2026, the US Federal Reserve publishes its interest rate decision, and futures markets mostly expect a hike. If you have a savings plan running on Bitcoin, the hon
On Wednesday, September 16, 2026, the US Federal Reserve publishes its interest rate decision, and futures markets mostly expect a hike. If you have a savings plan running on Bitcoin, the honest answer to the question of what you have to do now is: probably nothing. Two things are still worth checking, and beforehand rather than afterwards: exactly when your next instalment is executed, and how much headroom a running crypto loan still has.
This article explains what actually happens on September 16, which mechanism connects a US policy rate to your monthly Bitcoin purchase, and where the meeting day gets expensive for retail investors. It contains no price forecast, because nobody can seriously predict how the market will react to a decision that is already largely priced in.
What the Fed decides on September 16, 2026, and when the number arrives
The body that sets the US policy rate is called the Federal Open Market Committee, or FOMC: the monetary policy committee of the Federal Reserve, which meets eight times a year and sets the target range for the overnight rate between banks. The meeting runs over two days, September 15 and 16, 2026. The decision comes on the second day.
The Federal Reserve meeting calendar marks the date with an asterisk. That asterisk looks like a footnote and carries the most important information on the page: it flags the meetings at which the Fed publishes a Summary of Economic Projections. Those projections are the collected expectations of the central bankers on growth, unemployment, inflation and the future level of rates, and they reach several years ahead. After September, only two meetings remain in 2026, on October 27 and 28 and on December 8 and 9.
The time that matters
The decision is published at 18:00 UTC, which is 20:00 in central European summer time. The press conference starts half an hour later. For you that means: Wednesday evening between 20:00 and 21:00 CEST is the window in which prices on crypto exchanges get most turbulent. The Frankfurt stock market has long since closed by then; the crypto market keeps trading.
Where is the US policy rate now, and what does a 25 basis point step change?
The current target range for the overnight rate is 3.50 to 3.75 percent. It has been in place since July 30, 2026, as recorded in the Fed's implementation note for the July meeting. A basis point is one hundredth of a percentage point, so 25 basis points are 0.25 percentage points. If the step goes through, the range would afterwards sit at 3.75 to 4.00 percent.
Why expectations flipped at all can be pinned to a single number. US consumer prices in August were 3.4 percent higher than a year earlier, with the core rate at 2.4 percent; the largest single driver was petrol, up 3.9 percent. After the release on September 11, the probability of a September hike priced into futures markets jumped. The figures different houses quote for the CME FedWatch reading sit in a range of roughly 86 to 90 percent, after around 70 to 72 percent the day before. I am deliberately not smoothing that range: the value moves with every trading day, and the spread itself is the more honest piece of information.
The numbers come from CNBC's report on August consumer prices, which carries the FedWatch readings. Important for context: a priced-in probability reflects what the market has in the price. The value is a bet by futures traders and carries no predictive power beyond that, and that is exactly why prices move less on the expected step than on the deviation from it.
Why does the Bitcoin price react to a US Federal Reserve decision at all?
The connection is less mysterious than many headlines make it sound. A higher policy rate means that parking money risk-free earns more. Anyone getting four percent on overnight deposits or short-dated government bonds demands a higher compensation for anything riskier. Bitcoin pays no interest and consists exclusively of price movement. As the risk-free return rises, so does the bar Bitcoin has to clear.
On top of that comes the funding channel. A large share of short-term trading volume in the crypto market runs on borrowed money. When money gets more expensive, leveraged positions shrink and the market gets thinner. That explains why price moves on central bank days are often more violent than the news itself warrants.
What this means in practice for the coming days
At the time of writing, Bitcoin trades at around 76,700 US dollars, or roughly 66,200 euros; retrieved on September 14, 2026 at 00:40 UTC via CoinGecko's public price interface. In the preceding 24 hours the change was under one percent. That figure is a snapshot and no basis for a decision meant to work over years.
Should I pause my Bitcoin savings plan before the rate decision?
The short answer is no, and the reason lies in the purpose of a savings plan. A savings plan buys a fixed amount at fixed intervals, regardless of the price. It is the decision to stop making individual decisions. Anyone who pauses it ahead of a scheduled event has abolished it at exactly the moment it was built for.
What does make sense is checking once whether the instalment still fits your circumstances. If rising rates make your mortgage or your overdraft more expensive, the instalment is the lever, not the execution date. Which providers allow which minimum instalments, intervals and fees is set out in our comparison of Bitcoin savings plan providers, and with small instalments the fee side quickly becomes the largest cost block.
The difference between pausing and adjusting
Pausing means: you do not buy this month. Adjusting means: you keep buying, but with an amount you can sustain through a bad quarter as well. The first is a market forecast in disguise, the second is household budgeting. Only one of the two is something you can do reliably.
What dollar cost averaging achieves on a meeting day and what it does not
Dollar cost averaging describes a simple arithmetic phenomenon: anyone buying regularly for the same amount gets more units at low prices and fewer at high ones, so the average price ends up below the mean of the prices. No promise of returns comes with that, and no protection against losses either. The effect is a procedure that prevents timing errors.
On a central bank day the benefit shows particularly clearly, because the price move after the decision can go either way and the counter-move often follows within hours. A savings plan simply does not take part in that question. If you want to know how it stacks up against a lump sum purchase, we worked it through in our article on savings plans and lump sum purchases when buying more of August 24, 2026.
Crypto loans before September 16: what buffer your loan-to-value ratio needs
This is the part where a meeting day can do real damage. Anyone who has pledged crypto assets as collateral and taken out a loan against them is working with a loan-to-value ratio: the relation of the loan amount to the current value of the collateral. If the price of the collateral falls, that ratio rises. Once it crosses the provider's limit, an automatic sale follows. This forced sale is called liquidation, and it does not ask whether the move will be over again an hour later.
Two figures determine how well you sleep here. The first is the distance between your current ratio and the liquidation threshold. The second is the interest rate you pay on the loan, because variable rates in crypto loans track market rates and demand for the borrowed asset. Our overview "Crypto lending: interest rates and risks" of August 16, 2026 describes these mechanisms in detail.
The check that takes ten minutes
Log in once before Wednesday evening and note down two numbers: the price at which your position would be liquidated, and the distance between that price and today's level in percent. If that distance is in single digits, it is a state you should change regardless of the Fed. Either by topping up collateral or by repaying part of the loan.
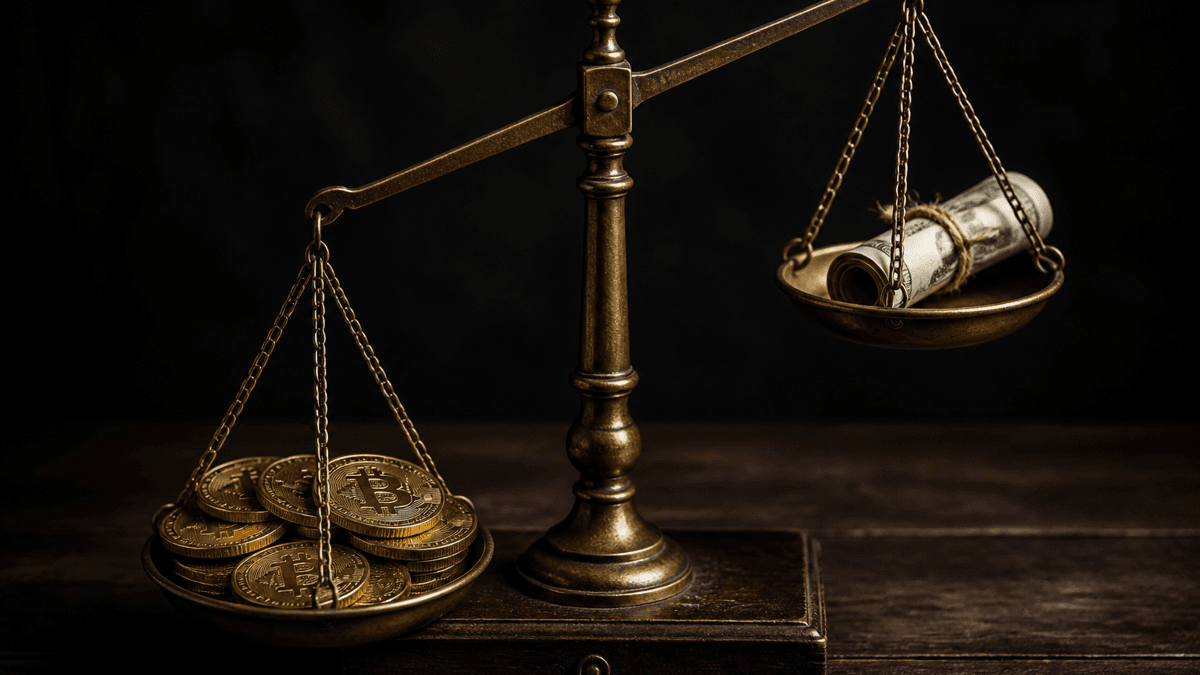
A higher policy rate makes the interest-bearing account heavier and the risky part of your assets relatively lighter. That shift in weight is the whole mechanism.
Why the projections matter more than the rate step itself
Because a 25 basis point hike is around nine tenths priced into the market, the actual information sits in the projections. Their best-known component is the dot plot: a scatter of points in which every member of the committee anonymously marks where they see the policy rate at year end. If that cloud shifts upwards, the committee is signalling further steps. If it stays where it is, the September step was a one-off response to the price data.
For a savings plan that is the only relevant question of the evening, and it is a question about months, not hours. A rate peak reached in December looks entirely different for long-term investors than a path pointing upwards well into 2027.
What analysts say and how to handle it
Around every meeting, price targets appear from institutions and individual analysts. Take them for what they are: expectations attributable to a name. Anyone quoting a price target should be able to name its source; without a name, all that remains is sentiment. And where expectations diverge, both sides belong side by side, the optimistic one and the cautious one.
Execution date, trading hours and spread: where the meeting day can cost you money
The spread is the gap between the price at which you can buy and the price at which you could sell. It is the part of the cost almost nobody calculates, because it does not appear on the statement. In turbulent market phases it widens, and that is exactly what happens in the hour after a central bank decision.
If your savings plan executes on the 16th or 17th of the month anyway, that is no reason to change anything; over years it evens out. But if you were planning to change the execution date regardless, a date in the quieter middle of the month between two central bank meetings is the less conspicuous choice. While you are at it, check whether your provider executes at a fixed time or at some point during the day; in the latter case the timing is out of your hands.
What runs differently with exchange-traded products
Anyone holding Bitcoin through an exchange-traded product rather than directly gains a second layer: those securities only trade during exchange hours. If the decision lands at 20:00 CEST, while German trading is closed, you only see the move the next morning at the open, and then all at once.
The only fixed appointment this week is the time of the release. Everything else about the meeting is expectation.
What the rate decision has to do with your holding period and your tax bill
Directly nothing, indirectly a great deal. Anyone holding Bitcoin as private assets in Germany can realise gains tax free once a year has passed; that one-year period is called the holding period and runs separately for every purchase. With a savings plan that means: you have as many holding periods as executed instalments.
The connection to the Fed arises the moment a price move tempts you to sell. Anyone selling after a violent evening move may realise gains from instalments that have not yet reached the one-year mark, and pays their personal income tax rate on them. The order in which the tax office assigns the units sold follows the first-in-first-out principle: the units bought first count as sold first. What that looks like in concrete terms with monthly instalments is set out in our article "Bitcoin savings plans and tax: holding period, FIFO and the exemption limit" of August 11, 2026.
The mistake that costs the most on central bank days
The most expensive mistake is rarely bad timing. What gets expensive is the unintended: a decision to sell in the evening, taken in reaction to a headline, which only reveals its price in the following year's tax return. What helps against that is a rule you write down before Wednesday, not on Wednesday.
Bitcoin savings plans and the rate decision: what to take away
- Let the savings plan run and check the instalment instead. Whether your amount, your interval and your fees still fit your situation decides more over the years than any single purchase date. You will find the providers' terms in our comparison of Bitcoin savings plans.
- Look at your loan buffer before Wednesday evening. Note the liquidation price and the percentage distance to today's price. If that distance is tight, top up collateral or repay part of the loan before the decision lands. The providers' terms and limits are in our comparison of crypto lending platforms.
- Keep your purchase records clean before you sell anything. With a savings plan, the date of every single instalment decides the tax on the sale. A portfolio tracker with a tax function takes that allocation off your hands; the selection is in our comparison of crypto tax tools.
(As of September 14, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)