The Hyperliquid Policy Center has formally called on the U.S. Securities and Exchange Commission to exclude crypto airdrops from the agency's definition of securities, a request that, if acte
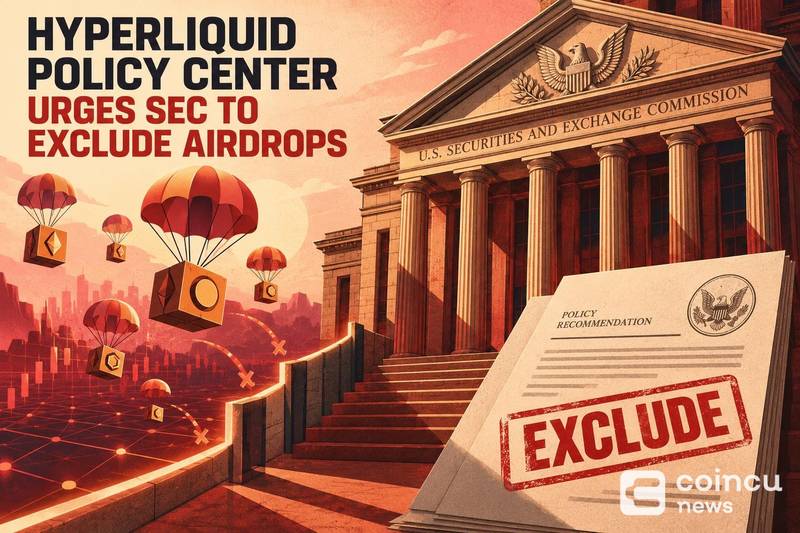
The Hyperliquid Policy Center has formally called on the U.S. Securities and Exchange Commission to exclude crypto airdrops from the agency's definition of securities, a request that, if acted upon, could reshape compliance obligations for token projects distributing assets to users at no cost. The proposal targets one of the most consequential unresolved questions in digital-asset regulation: whether distributing tokens freely to wallet holders constitutes an investment contract subject to federal securities law.
Hyperliquid Policy Center Calls for Airdrop Exclusion
The Hyperliquid Policy Center, a policy and advocacy body associated with the Hyperliquid ecosystem, has directed its request to the SEC's dedicated crypto task force, which was established to develop clearer regulatory frameworks for digital assets. The center's position is that airdrops, defined as the unilateral distribution of tokens to wallet addresses without payment or active purchase, lack the core characteristics of securities transactions and should be formally excluded from that classification. For related coverage, see Hyperliquid Gets $14.58M First USDC Reserve Income.
The requested outcome is specific: a categorical exclusion or safe-harbor provision that would clarify airdrops do not meet the investment-contract test under existing law. Absent such clarity, token issuers operating in the United States face the risk that distributing tokens without registration could be treated as an unregistered securities offering, regardless of whether recipients paid anything to receive them. For related coverage, see Hyperliquid Reports $14.58M First USDC Reserve-Income Payment.
What the policy center is asking the SEC to clarify
At the core of the request is a question of economic substance. The Hyperliquid Policy Center argues that a recipient who receives tokens without paying for them has not made an "investment of money" in a common enterprise, which is one of the foundational prongs of the Howey Test, the four-part framework U.S. courts use to determine whether an asset qualifies as an investment contract subject to SEC oversight. For related coverage, see BlackRock Files Bitcoin Managed Protection ETF for IBIT Downside Protection.
The policy center's position, as framed by the headline and regulatory context, is that the SEC should issue guidance or rulemaking that draws a clear line between a purchased token offering, which may satisfy Howey criteria, and a free distribution to existing wallet holders or protocol users, which arguably does not. No SEC response, acceptance, or rejection of this request has been confirmed in the available materials as of the date of this article.
Why the Securities Classification of Airdrops Matters
Airdrops have become one of the dominant mechanisms through which blockchain protocols distribute governance rights, incentivize early adoption, and reward user participation. A securities classification imposes registration requirements, disclosure obligations, and potential liability on both the issuing project and, in some interpretations, on secondary market platforms that facilitate trading of the distributed tokens.
How securities treatment can affect token distributions
Under the securities framework, any project distributing tokens to U.S. persons would need either to register the offering with the SEC or qualify for an exemption, a process that carries significant legal costs and restricts who can receive the tokens. For protocols that airdrop to thousands or millions of wallet addresses, the compliance burden could be operationally prohibitive. The SEC's crypto task force has acknowledged the complexity of applying legacy securities law to novel token distribution models, though no binding guidance specific to airdrops has been issued.
The classification question also touches recipients directly. If airdropped tokens are securities, recipients in jurisdictions with securities trading restrictions may face legal uncertainty when they trade or transfer those assets. Projects frequently geo-block U.S. IP addresses from airdrop claim interfaces as a precautionary measure, a practice that underscores how unsettled the legal landscape remains.
The Hyperliquid ecosystem itself has navigated these regulatory questions amid growing attention to its compliance posture. Hyperliquid's engagement with U.S. policymakers reflects a broader strategy by the project to operate within regulatory frameworks rather than around them, as noted in coverage of discussions about bringing Hyperliquid to the U.S. compliantly.
Potential Impact on Crypto Projects and Airdrop Recipients
A formal SEC exclusion or safe harbor for airdrops would carry immediate practical consequences for how token projects structure their launches. Currently, legal counsel routinely advises projects to limit or exclude U.S. participation in airdrop programs specifically because of unresolved securities risk. A clear regulatory boundary would allow compliant projects to include U.S. wallet holders without triggering registration requirements, broadening participation in governance and incentive programs.
What clearer SEC treatment could change for token launches
Token launch sequencing would likely shift if airdrops were formally excluded from securities treatment. Projects could distribute governance tokens to early users before or alongside liquidity bootstrapping events, rather than choosing between the two out of caution. Platforms facilitating airdrop claims, including decentralized exchanges and eligibility portals, could operate with greater confidence that listing or surfacing airdropped tokens does not expose them to securities intermediary liability.
For recipients, regulatory clarity would reduce the ambiguity around tax and disclosure treatment that frequently accompanies airdrop participation. While tax treatment of airdrops falls under IRS jurisdiction rather than the SEC's, a clear determination that airdropped tokens are not securities removes one layer of compliance uncertainty that discourages retail participation and institutional engagement with airdrop programs.
The stakes for the broader DeFi sector extend beyond individual projects. Hyperliquid's financial trajectory, including its first USDC reserve income payment of $14.58 million, demonstrates the scale at which decentralized protocols now operate, making regulatory predictability around token distribution a material business concern rather than a theoretical legal question.
Projects that rely on token distributions to align incentives between protocol developers and users argue that securities classification fundamentally mischaracterizes the economic function of airdrops. A governance token distributed to a user who has already interacted with a protocol does not represent a speculative investment in an enterprise managed by others; it represents a stake in a decentralized system the user has already participated in. This framing, if adopted by the SEC, would mark a significant departure from the agency's historically expansive application of the investment-contract test to digital assets.
What to Watch Next From the SEC
The SEC's crypto task force, operating under a mandate to produce clearer regulatory frameworks for digital assets, represents the most direct institutional pathway through which a formal response to the Hyperliquid Policy Center's request could emerge. The task force has hosted roundtables with industry participants and published conceptual frameworks on topics including token classification, but no timetable for airdrop-specific guidance has been confirmed in materials available as of this writing.
Policy signals that could shape airdrop rules
Several distinct regulatory outputs could clarify the airdrop question without requiring full notice-and-comment rulemaking. The SEC could issue a no-action letter to a specific project conducting an airdrop, signaling that the agency would not pursue enforcement. It could publish interpretive guidance addressing the conditions under which token distributions fall outside the Howey Test. Alternatively, Congress could intervene through legislation that explicitly carves out certain token distribution methods from securities definitions, an approach that crypto-focused political action groups have been actively funding, as seen in recent political spending by Fairshake-affiliated PACs targeting pro-crypto candidates.
None of these outcomes carries a confirmed timeline based on the available materials. The Hyperliquid Policy Center's request is an advocacy position directed at a regulatory body that retains full discretion over whether and how to respond. Readers should treat the request as the opening of a policy dialogue rather than as an imminent regulatory change.
The practical question for market participants is whether the SEC's crypto task force prioritizes airdrop classification within its current workload, which also encompasses spot ETF oversight, exchange registration, and stablecoin policy. Enforcement actions against specific projects that conducted large airdrops could accelerate the need for formal guidance even absent a proactive rulemaking process. Conversely, sustained congressional pressure on the SEC to provide clarity before bringing enforcement actions could create a de facto grace period that benefits airdrop programs operating in good faith.
FAQ
What is the Hyperliquid Policy Center asking the SEC to do?
The Hyperliquid Policy Center is urging the SEC to exclude crypto airdrops, defined as free token distributions to wallet holders, from the agency's definition of securities. The request asks for a formal carve-out or clarifying guidance that would confirm free token distributions do not constitute investment contracts subject to federal securities regulation.
Would an SEC exclusion mean every airdrop is unregulated?
Not necessarily. Even if the SEC issued guidance excluding airdrops from securities definitions, other regulatory frameworks could still apply, including commodity regulations overseen by the CFTC, IRS tax rules on income recognition, and anti-money-laundering obligations that apply to token distributions. The proposed exclusion addresses securities classification specifically, not the full regulatory landscape for token distributions. Any SEC guidance would also likely include conditions, and distributions structured to function as de facto sales might not qualify for an exclusion even under a favorable framework.
Has the SEC made a decision on this request?
No SEC decision, response, or formal acknowledgment of the Hyperliquid Policy Center's request has been confirmed in the materials available as of the publication of this article. The request is directed at the SEC's crypto task force, which has the mandate to develop clearer digital-asset policy but has not issued binding airdrop-specific guidance. The difference between a policy advocacy request and a binding regulatory rule is significant; the former initiates a conversation, while the latter changes legal obligations.
Why does this matter for holders and builders in the Hyperliquid ecosystem?
Hyperliquid operates as a decentralized perpetuals exchange and broader financial infrastructure layer, and token distributions are a core mechanism by which its ecosystem aligns participants with protocol growth. Regulatory uncertainty about airdrop classification creates friction for projects that want to reward users, build governance communities, and distribute ownership broadly, all of which are central to Hyperliquid's operating model. A formal SEC exclusion would lower the legal barrier to including U.S. participants in future distribution programs, which carries direct implications for protocol adoption and user base growth.
Additional source references: source document 1.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Cryptocurrency and digital asset markets carry significant risk. Always do your own research before making decisions.
The post Hyperliquid Policy Center Urges SEC to Exclude Airdrops was initially published on Coincu.