Latin America’s fast-growing stablecoin payment ecosystem may be more reliant on a limited set of “wholesale” liquidity providers than public company data suggests, according to researchers a
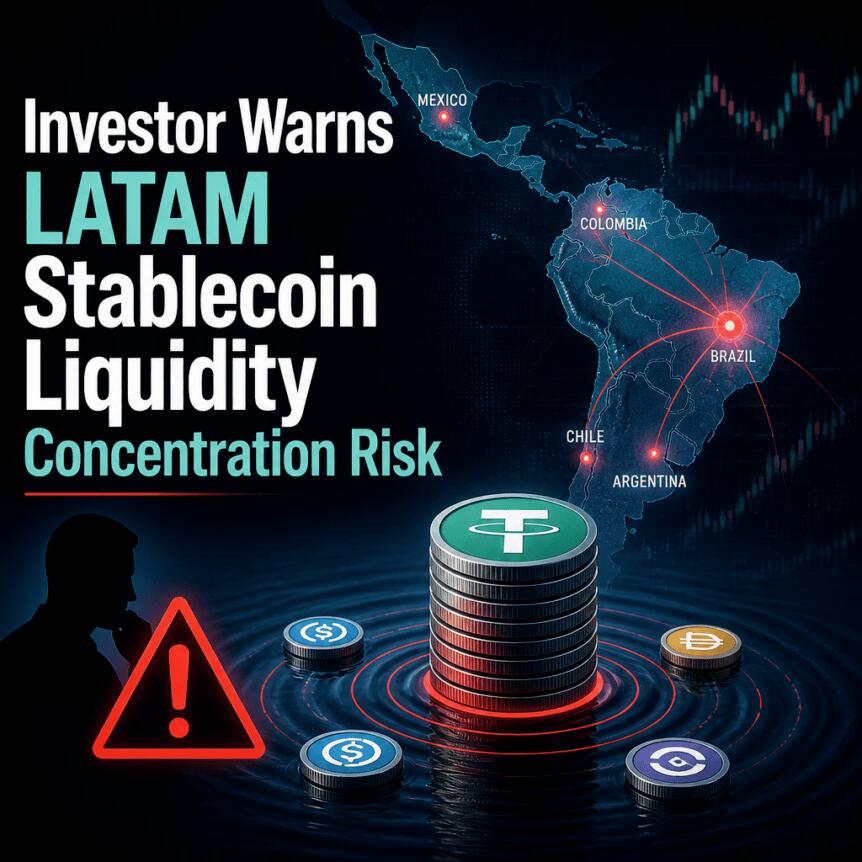
Latin America’s fast-growing stablecoin payment ecosystem may be more reliant on a limited set of “wholesale” liquidity providers than public company data suggests, according to researchers at Varys Capital and Verda Ventures. In a report that analyzed Verda’s Stablescape database, the team warns that if banking access is disrupted for a key provider, users could face slower or more expensive cash-outs into local currencies.
The concern centers on what the report calls “fragility concentrated in the thinnest layer” of the stablecoin-to-fiat conversion chain—where stablecoins meet regulated banking rails. Verda Ventures partner Amit Chu, speaking to Cointelegraph, argued that the industry may be structured around a small number of specialists even if many entities appear in public records as liquidity sellers.
Key takeaways
- Varys Capital and Verda Ventures reviewed 494 regional companies, but identified only 16 whose primary business is providing wholesale stablecoin-to-fiat liquidity.
- The research suggests fragility may be concentrated among a small group of conversion desks, particularly at the point where cash-out to local bank accounts happens.
- Verda’s Stablescape database does not measure transaction volumes or market share, so concentration cannot be fully quantified from public data alone.
- Chu says licensing and clearer rules for liquidity providers could reduce concentration by making it easier for banks to serve more participants.
- Local-currency stablecoins and broader on-chain settlement options may allow more market makers to participate and improve redundancy.
A thin layer behind stablecoin cash-outs
The report’s core finding is a mismatch between the number of companies involved in stablecoin payments and the smaller number of specialists that primarily provide wholesale stablecoin-to-fiat liquidity. While researchers analyzed 494 businesses in Latin America, only 16 were classified as primary wholesale liquidity providers, alongside corporate treasury and credit roles, according to the report described by Chu.
Chu said the risk is not just that liquidity providers are fewer than retail-facing services, but that the ecosystem may route currency risk through the same desks and exchanges. He noted that public data alone cannot reveal whether liquidity sellers keep the risk themselves or pass it onward. However, his view is that the second pattern is more likely, which he believes explains the fragility highlighted in the analysis.
What happens if a provider loses banking access
Stablecoins have become increasingly important in Latin America’s crypto activity, with Chainalysis data cited in the report indicating stablecoins accounted for 32.1% of cross-border crypto value by June 2026. The same Chainalysis reporting also cited stablecoins at 22.1% of domestic P2P activity and 17.6% of personal wallet balances in the region.
That growing usage raises the stakes of operational bottlenecks. Chu argued that a disruption tied to a key liquidity provider—especially one that affects banking relationships—could leave users holding stablecoins without smooth routes to convert them into local currency. In practical terms, he said the “problem would be at the exits,” where spreads could widen and cash-outs to local bank accounts could slow or even pause. He also warned that funds in transit with a failed desk could become stuck.
Importantly, the report does not claim that the entire ecosystem is controlled by a single player. Instead, it suggests that even if stablecoin adoption is broad, the cash-out mechanics may be dependent on a narrow set of intermediaries with reliable banking access.
Concentration is hard to measure—so what should investors watch?
Chu stressed that the analysis cannot determine how concentrated liquidity truly is, because Stablescape does not track transaction volumes and does not provide market share metrics. He also pointed out that the database likely undercounts liquidity supply by excluding some entities that may provide liquidity from categories defined elsewhere.
Even with these limitations, Chu said Verda believes some businesses classified as liquidity providers elsewhere may still rely on the same underlying desks. That matters because market structure can be obscured by layered service models: a customer-facing company may appear to offer direct liquidity, while the conversion process ultimately depends on upstream counterparties.
At the same time, Chu cautioned against assuming that fewer dealers automatically signals a problem. In mature FX markets, there are often far fewer dealers than customer-facing firms, he said. What distinguishes healthy systems from fragile ones is redundancy and capital—meaning that multiple independent, well-capitalized desks should be able to handle flows, each with separate banking relationships, and that wallets should be able to route through more than one provider.
Licensing, local-currency stablecoins, and redundancy
According to Chu, licensing is the most direct lever to reduce concentration. Clearer regulatory pathways could make it easier for banks to serve liquidity providers more broadly, increasing the number of capable desks and reducing the likelihood that disruptions at a small number of institutions ripple across the entire cash-out pipeline.
He also highlighted local-currency stablecoins as a potential structural improvement. By enabling settlement in local terms and allowing more participants to quote or settle on-chain, local-currency products could expand who can efficiently manage conversions rather than funneling activity through a few global desks.
Chu said that while some global trading firms have started quoting Latin American currency pairs, the broader question remains whether market design and banking access allow for multiple independent liquidity routes. Without that, the ecosystem may grow in adoption while still depending on a narrow “conversion layer” that is vulnerable to banking access constraints.
More broadly, the report situates Latin America as a growth opportunity—particularly for cross-border payment solutions—while arguing that fragmented banking systems and costly transfers create demand for services that make moving money between countries easier. The new warning is that stablecoin rails may reduce friction for users, but they do not automatically eliminate dependence on regulated endpoints where local currency liquidity and banking rails connect.
For users, wallet providers, and liquidity operators, the key uncertainty is how much upstream liquidity is shared behind the scenes and how quickly alternative desks can step in if one provider is impaired. Observers should watch whether regulators expand licensing pathways and whether local-currency stablecoins and multi-route routing meaningfully increase operational redundancy in cash-out channels.
This article was originally published as Investor Warns LATAM Stablecoin Liquidity Concentration Risk on Crypto Breaking News – your trusted source for crypto news, Bitcoin news, and blockchain updates.