Key Takeaways ORCL shares have surrendered their entire 2025 rally in 2026 but remain valued at only 17.2x projected Fiscal 2027 non-GAAP earnings of $8.14 per share. Management projects an a
Key Takeaways
- ORCL shares have surrendered their entire 2025 rally in 2026 but remain valued at only 17.2x projected Fiscal 2027 non-GAAP earnings of $8.14 per share.
- Management projects an ambitious 34% revenue expansion for Fiscal 2027, with total sales expected to exceed $90 billion.
- Elevated borrowing costs and $19.9 billion in fresh equity issuance are constraining earnings-per-share momentum to approximately 18.5% growth.
- Mizuho maintained its Outperform stance with a $320 target, highlighting robust operational performance and expanding cloud infrastructure.
- Consensus among analysts remains at Strong Buy, with a mean target of $251.77 suggesting potential gains of roughly 79%.
The year 2026 has proven challenging for Oracle shareholders. Trading near $144.83 on Tuesday, ORCL has completely reversed its previous year’s advance, even as the enterprise software giant’s fundamental operations continue expanding.
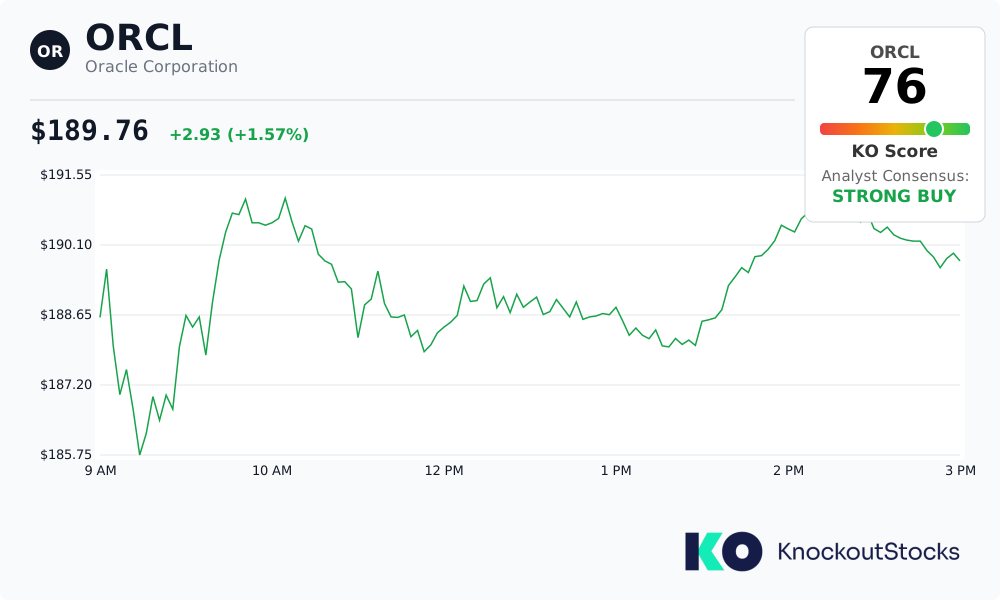 Oracle Corporation, ORCL
The stock’s decline masks a compelling financial narrative. Oracle’s management team projects Fiscal 2027 revenues surpassing $90 billion, representing a remarkable 34% annual increase. Such top-line acceleration would mark the company’s strongest revenue performance in more than ten years.
Oracle Cloud Infrastructure stands at the center of this expansion. OCI delivered exceptional 120% constant-currency growth compared to the prior-year quarter. Artificial intelligence workloads continue fueling robust demand, with executives noting accelerated deployment timelines for new capacity installations.
The company’s latest Q1 Fiscal 2027 financial report exceeded Wall Street’s expectations across both revenue and profitability metrics. Adjusted earnings reached $1.92 per share, climbing nearly 30% year-over-year. This performance represents the third straight quarterly period where Oracle delivered above-consensus results on revenue and earnings, per Mizuho’s analysis.
Mizuho maintained its Outperform designation while sustaining a $320 price objective. The investment firm highlighted Oracle’s disciplined cost management, noting operating margins improved approximately 35 basis points annually despite headwinds to gross profitability.
Profitability Expansion Encounters Obstacles
While topline momentum appears impressive, earnings-per-share dynamics present a more nuanced picture. The company introduced $19.9 billion worth of additional shares to finance its growth initiatives. This shareholder dilution, coupled with an environment of higher borrowing costs, constrains non-GAAP EPS advancement to roughly 18.5% for the fiscal year—significantly trailing revenue expansion rates.
Oracle maintains a substantial debt load of $125.3 billion, positioning it among the technology sector’s most leveraged enterprises. The company recorded negative free cash flow of $5.4 billion during Q1 2027, extending a pattern established in the prior fiscal period. Leadership indicates Fiscal 2027 and 2028 will represent peak capital investment years, with operations expected to transition toward self-funding thereafter.
Following just a single quarter into Fiscal 2027, management elevated its outlook, projecting net capital expenditures will not exceed $70 billion.
Street Perspectives on ORCL
Wall Street sentiment skews decidedly positive, though viewpoints vary. UBS elevated its price objective to $250. DA Davidson preserved its Buy recommendation with a $225 target. Bernstein maintained its Outperform assessment at $325. Conversely, Freedom Broker reduced its target to $205 while Stifel lowered expectations to $200, both expressing concerns regarding margin compression.
According to InvestingPro analytics, 14 analysts increased their earnings projections ahead of the next reporting window. The stock’s PEG ratio registers at 0.51, which InvestingPro identifies as trading below intrinsic value.
The Wall Street community assigns ORCL a Strong Buy rating overall, reflecting 25 Buy recommendations and four Hold ratings issued over the trailing three-month period. Zero analysts presently rate the shares as a Sell.
The consensus price target among analysts stands at $251.77, suggesting approximately 79% appreciation potential from present trading levels.
The post Oracle (ORCL) Stock Tumbles in 2026 Despite Analysts Projecting 79% Rally Ahead appeared first on Blockonomi.