Key Takeaways SanDisk (SNDK) shares declined 17% during Q3 while maintaining a remarkable 628% year-to-date surge. Bernstein analysts maintain their Outperform rating with a $3,000 price obje
Key Takeaways
- SanDisk (SNDK) shares declined 17% during Q3 while maintaining a remarkable 628% year-to-date surge.
- Bernstein analysts maintain their Outperform rating with a $3,000 price objective, suggesting 73% potential appreciation.
- Micron (MU) also received an Outperform rating from Bernstein with a $1,300 target, indicating 22% growth potential.
- Memory chip pricing for DRAM and NAND is projected to increase approximately 20% sequentially in Q3 2026.
- The company’s October 29 earnings release is viewed as a critical upcoming catalyst for the stock.
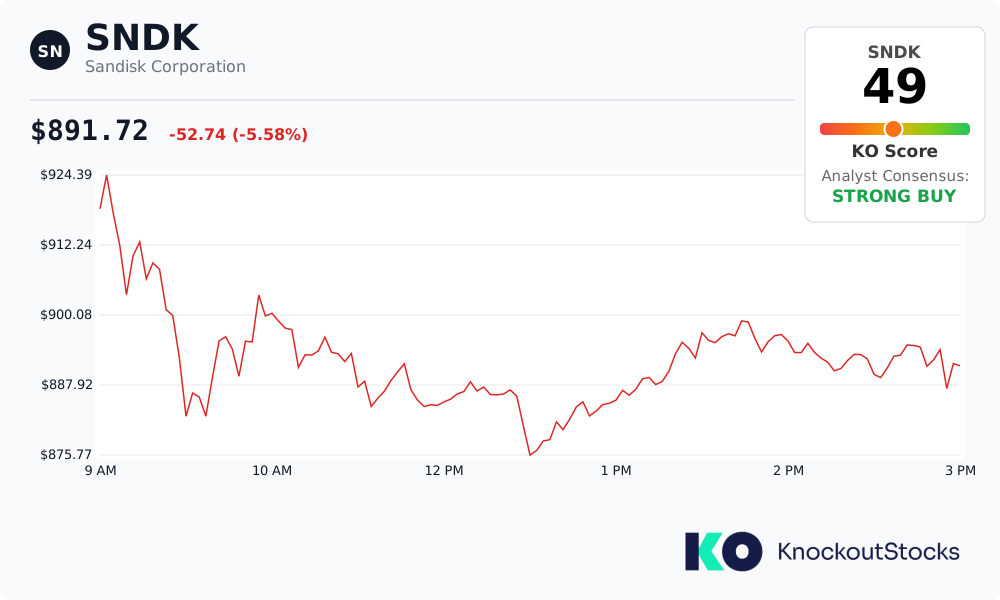
Shares of SanDisk (SNDK) finished Wednesday’s trading session at $1,739.89, posting a modest 0.59% daily gain. The memory chip manufacturer experienced a 17% pullback throughout the third quarter, contrasting sharply with the S&P 500’s 4.3% advance during the identical timeframe. Nevertheless, the stock maintains an extraordinary 628% year-to-date rally.
 Sandisk Corporation, SNDK
Bernstein analyst Mark Newman continues to champion the stock’s prospects. The investment firm reiterated its Outperform stance alongside a $3,000 price objective for SanDisk, representing a substantial 73% appreciation opportunity from present valuation levels, per TipRanks data.
The firm similarly reaffirmed its positive outlook on Micron (MU), sustaining an Outperform designation with a $1,300 target that suggests 22% upward movement. Both recommendations rest upon a unified thesis: memory semiconductor supply remains constrained, and this tightness appears durable.
Bernstein’s forecast anticipates traditional DRAM and NAND pricing will surge approximately 20% sequentially during Q3 2026. The research firm believes this supply constraint environment could persist through 2027, although extended contractual arrangements might establish ceiling limitations on pricing expansion.
The Strategic Importance of Long-Term Agreements
Newman highlighted eight extended agreements SanDisk has secured, collectively valued at $93.9 billion. These commitments are projected to fulfill approximately half of SanDisk’s bit requirements in 2027, expanding to two-thirds coverage in 2028.
These arrangements incorporate $16.5 billion in financial commitments, featuring both minimum and maximum pricing provisions. This framework offers SanDisk downside protection should NAND pricing experience future deterioration.
During its August investor presentation, SanDisk communicated long-range projections for mid-to-high teens revenue expansion. Management also provided guidance targeting approximately 80% non-GAAP gross margin performance spanning fiscal years 2028 through 2030.
Citigroup analyst Asiya Merchant noted that SanDisk’s investment narrative emphasizes a transformation in NAND demand patterns toward extended structural growth. She identified datacenter requirements, hyperscale artificial intelligence infrastructure, and enterprise solid-state drive adoption as emerging expansion catalysts, supplanting traditional consumer refresh cycles.
Micron’s Results May Preview Industry Trends
Market participants could receive preliminary validation of Bernstein’s memory sector outlook when Micron unveils its fiscal fourth-quarter performance. Consensus projections anticipate Micron’s revenue will surge 354% to reach $51.4 billion, while earnings are forecast to climb to $31.73 per share compared with $3.03 in the prior-year period.
Bernstein’s Mark Li elevated his Micron projections as well. His revised forecast calls for fiscal 2026 revenue of $130.1 billion, up from his previous $122.6 billion estimate, with adjusted earnings reaching $73.78 per share versus his earlier $67.39 projection.
Broader Wall Street sentiment demonstrates slightly more conservative positioning than Bernstein’s outlook. TipRanks’ aggregated Micron price target of $1,469.25 suggests 38% appreciation potential, while the consensus SanDisk objective of $2,195.29 implies 27% upside.
Market observers have attributed the Q3 weakness in SanDisk shares to profit-taking following the dramatic year-to-date advance, combined with persistent concerns regarding AI infrastructure spending momentum and potential NAND pricing softness in 2027. Industry watchers emphasize that fundamental business conditions remain intact despite the price correction.
SanDisk’s scheduled October 29 earnings announcement looms as the next significant milestone for evaluating whether the memory sector growth narrative maintains validity.
The post SanDisk (SNDK) Stock: Bernstein Projects 73% Rally Despite Q3 Decline appeared first on Blockonomi.