South Korea Won Stablecoin: Who Will Control Korea's Next Digital Won? The South Korea won stablecoin plan has moved a big step forward. Seoul’s financial regulator has now said, on the recor
South Korea Won Stablecoin: Who Will Control Korea's Next Digital Won?
The South Korea won stablecoin plan has moved a big step forward. Seoul’s financial regulator has now said, on the record for the first time, that a technology company can be the single largest owner of a company issuing a coin tied to the Korean won, as long as lenders together hold more than half.
Here is what was said, how the plan would work, and what may still change before it becomes law.
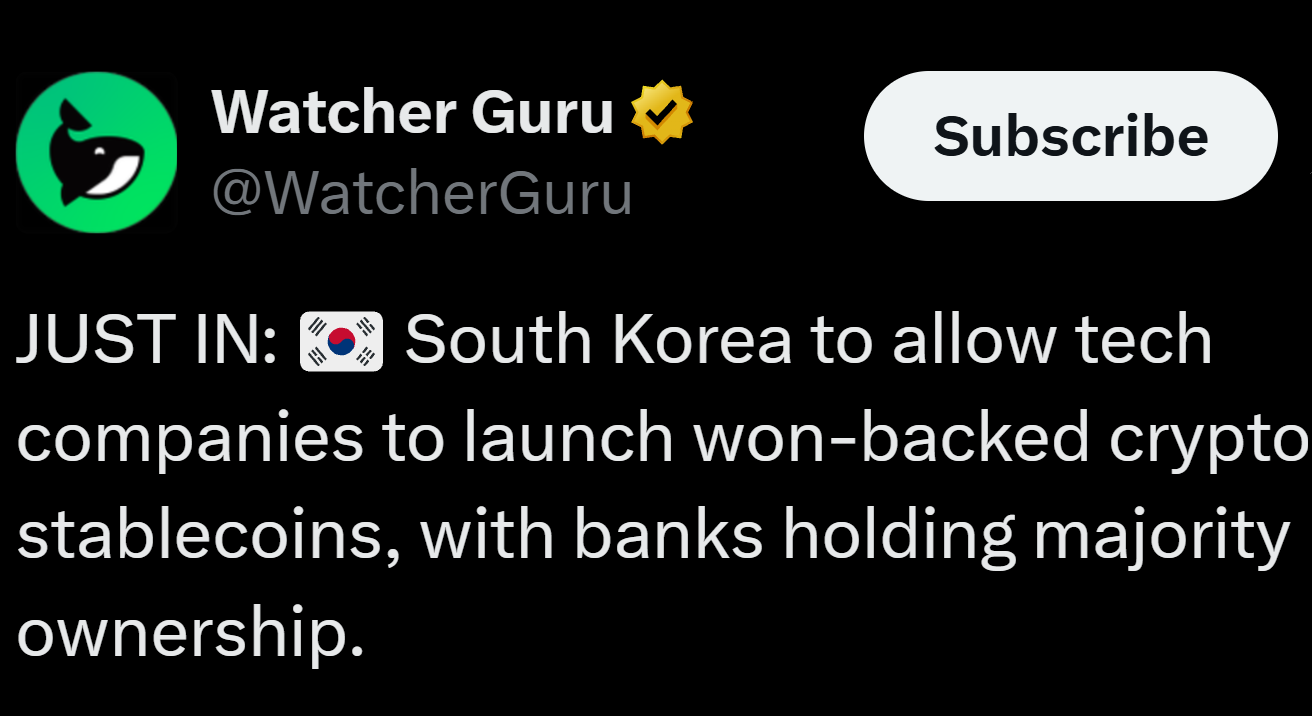
Source: Post on X
South Korea Won Stablecoin: What the Regulator Said
On 12 November, Yoo Young-joon, director general for digital finance policy at the Financial Services Commission (FSC), spoke at a forum in Seoul.
As explained ina detailed report published on 16 November, he said no rule stops a technology firm from being the biggest shareholder of an issuer, and that lenders alone cannot drive innovation.
The main points from his remarks:
Lenders would not issue or run the coins themselves. They would join as shareholders in a separate company.
They can add extra money if a coin ever needs it, and they already run checks against money laundering.
The bank majority is meant as a trust tool for the early stage. The door stays open to widening the list of allowed issuers later, after problems and legal gaps are reviewed.
These comments were made at a forum, not in a published FSC document, so the final wording of the law may differ.
How the Bank-Majority Plan Works
The government’s working plan would give issuing rights first to groups in which banks hold “50% plus one share”, which simply means just over half.
The same report says lawmaker Kang Jun-hyun, who has worked on the Digital Asset Basic Act, described talks about letting a tech company be the largest shareholder instead of requiring one single bank to hold that spot.
Here is a simple example, only for understanding. Five lenders could own 11% each, which is 55% together, while an app company owns 45%.
Lenders hold the majority, yet the app company is the biggest single owner.
There is one weak point. If no single bank has a big stake, it is unclear who steps in when extra money is needed in a crisis.
Each bank may decide its small share is not worth defending. A shareholder agreement or a licence condition may be needed to solve this.
Why Tech Firms and Exchanges Are Watching
An issuer earns money in two places: interest on the reserves backing the coins, and distribution, meaning the app where people hold and spend them.
Under this plan, lenders would own most of the issuer, while a platform could own the biggest single stake and run the customer-facing app.
Naver Financial and Dunamu: Naver Financial plans to buy Dunamu, which runs the Upbit exchange. The Fair Trade Commission began formal review on 10 November and listed 10 affected markets, including the future won coin market.
Industry views: Suh Byung-yoon of DSRV said limiting issuance to banks has few parallels elsewhere. Ryu Hong-ryeol of VIDEX argued that licences should depend on reserve management and the ability to redeem coins.
Market size: Figures cited at the forum show about 11 million crypto exchange accounts in Korea, roughly a fifth of the population, while more than 99% of the global market for such coins is still in dollars.
Taiwan Takes a Different Route
Taiwan’s regulator published its own draft on 6 November in itsofficial gazette.
Both places want lenders in control, but they differ on who leads.
Point
South Korea (regulator’s stance)
Taiwan (draft rule)
Bank share
Banks together hold a majority (50% plus one share)
Banks and financial holding companies together hold over 50%
Single owner
A tech firm may be the largest shareholder
One bank or holding company must hold over 25%
Legal status
Bill not yet published
Draft, with comments open until mid-December
Other limits
Banks join as shareholders in a separate company
At least NT$300 million paid-in capital, issuing as the only business, reserves held in trust at a different bank, no lending
In short, Taiwan wants one named bank in charge. Seoul prefers a group of lenders as a safety net, with a platform steering the business.
What Happens Next
The plan is still moving through the process, and nothing is final. Reports say the FSC is expected to present the main parts of the Digital Asset Basic Act in November, while lawmakers remain divided over the bank-majority condition.
Step one: the licensing law, meaning the Digital Asset Basic Act.
Step two: changes to the Electronic Financial Transactions Act and commercial laws, which are needed before real payments.
Step three: launch of actual products.
Related date: the separate framework for tokenized securities starts on 4 February 2027, according to the FSC.
Any South Korea won stablecoin launch date depends on this order. Key questions remain, such as whether the 50% rule becomes a statute, a licence condition or only guidance, and whether any single bank must hold a minimum stake.
Conclusion
The regulator’s message is clear: lenders hold the majority, but tech platforms can lead.
The South Korea won stablecoin debate is not over, because the bill is still pending and Taiwan’s draft shows another path.
Readers should wait for the published text before assuming any rule is final.
Disclaimer
This article is for educational and informational purposes only and is not financial or investment advice. Crypto assets are high risk, their prices can be very volatile, and you can lose some or all of your money. Always do your own research and consider speaking with a licensed financial advisor before making investment decisions.