The U.S. Senate is heading toward a key procedural vote on September 15 on crypto market-structure legislation, after more than a year of negotiations over who regulates digital assets and ho
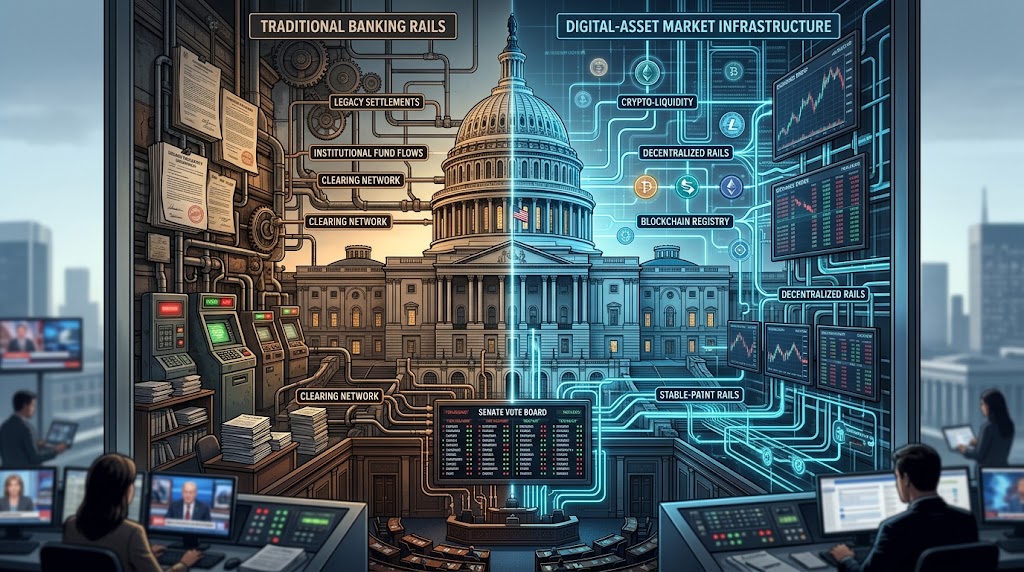
The U.S. Senate is heading toward a key procedural vote on September 15 on crypto market-structure legislation, after more than a year of negotiations over who regulates digital assets and how far the rules should reach.
The timing is important because the argument is no longer simply whether the United States needs a crypto framework. The House already passed the CLARITY Act framework, and Senate committees have spent months trying to turn market structure into legislation that can survive a closely divided chamber. The remaining fights now sit in the details: stablecoin economics, anti-money-laundering obligations, decentralized finance, enforcement authority and conflicts of interest.
President Donald Trump agreed over the weekend to additional ethics provisions sought by senators whose votes may be needed to move the bill forward, according to the Associated Press. Reuters reported earlier that the crypto industry and banking groups had both intensified lobbying ahead of the vote.
The September 15 Vote Is Not Final Passage
A procedural vote is a gate, not the finish line. If the Senate advances the legislation, lawmakers would still need to resolve text, amendments and any differences with the House before a final bill could become law.
That distinction matters for markets. Crypto legislation is often traded as a binary headline — passed or failed — even when Congress is several steps away from a final statute. Optimisus made the same point in its earlier coverage of the CLARITY Act’s Senate deadline: the bill can be directionally important without being legally finished.
The current debate is therefore best read as a test of whether a durable coalition exists for comprehensive digital-asset rules. A successful procedural vote would show that the Senate is willing to keep negotiating. A failure would make the legislative calendar substantially harder as attention shifts toward the midterm cycle.
The Ethics Fight Became a Market-Structure Fight
The newest bargaining is unusual because personal financial-conflict rules have become part of the same package as exchange oversight and token classification.
AP reported that the proposed ethics language would restrict certain elected officials and their families from issuing digital assets and could require stronger separation between public office and significant crypto interests. Another point of negotiation would give state attorneys general enforcement authority alongside federal agencies in specified circumstances.
Supporters frame those provisions as necessary credibility safeguards for a sector seeking federal legitimacy. Critics of broader state enforcement worry that a national market could end up facing politically inconsistent enforcement across jurisdictions. Both concerns can be true at the same time. A market-structure law is only as predictable as the institutions allowed to enforce it.
Banks and Crypto Firms Are Fighting Over the Same Pool of Money
The banking industry’s resistance is not mainly about whether bitcoin can trade. It is about what happens when dollar-denominated crypto products begin behaving like bank products.
Banking groups have pushed lawmakers to tighten treatment of stablecoin rewards and related arrangements, warning that yield-bearing or reward-bearing stablecoins could pull deposits away from community banks. Crypto firms argue that restricting rewards would protect incumbent banks from competition rather than protect consumers.
That dispute is economically more important than it sounds. Stablecoins have moved from an exchange settlement tool into payments, treasury management, cross-border transfers and onchain credit. Optimisus recently covered PYUSDx crossing $100 million in processed volume and the expansion of stablecoins into onchain credit infrastructure. Once digital dollars compete for idle cash, the line between crypto policy and banking policy disappears.
A Rulebook Would Not Remove Crypto Risk
Market-structure legislation can clarify which regulator oversees which activity, create registration paths and establish disclosure duties. It cannot make a token solvent, an exchange secure or a smart contract correct.
The distinction is especially important because the next phase of crypto regulation is increasingly about infrastructure rather than prohibition. The SEC is separately reconsidering how advisers and funds can custody digital assets, a process Optimisus covered in its article on the crypto custody overhaul sent to the White House. Market structure and custody rules together determine who can legally touch an asset; neither guarantees that the asset deserves to be held.
What Actually Matters After the Vote
If the Senate advances the bill, the next questions are more specific than ‘is Washington pro-crypto?’ Watch which agency receives primary authority over different token activities, how decentralized protocols are treated, whether stablecoin rewards survive, how state enforcement is bounded, and what the final conflict-of-interest provisions require.
Those details will decide whether the law creates one national operating framework or simply moves crypto’s uncertainty from courtrooms into compliance departments.
The industry’s biggest regulatory milestone may therefore be less dramatic than the market wants. The real win is not a headline saying crypto has been legalized. It is a rulebook boring enough that exchanges, banks, funds and developers know what happens before they launch the next product.
This is not financial advice.
Sources