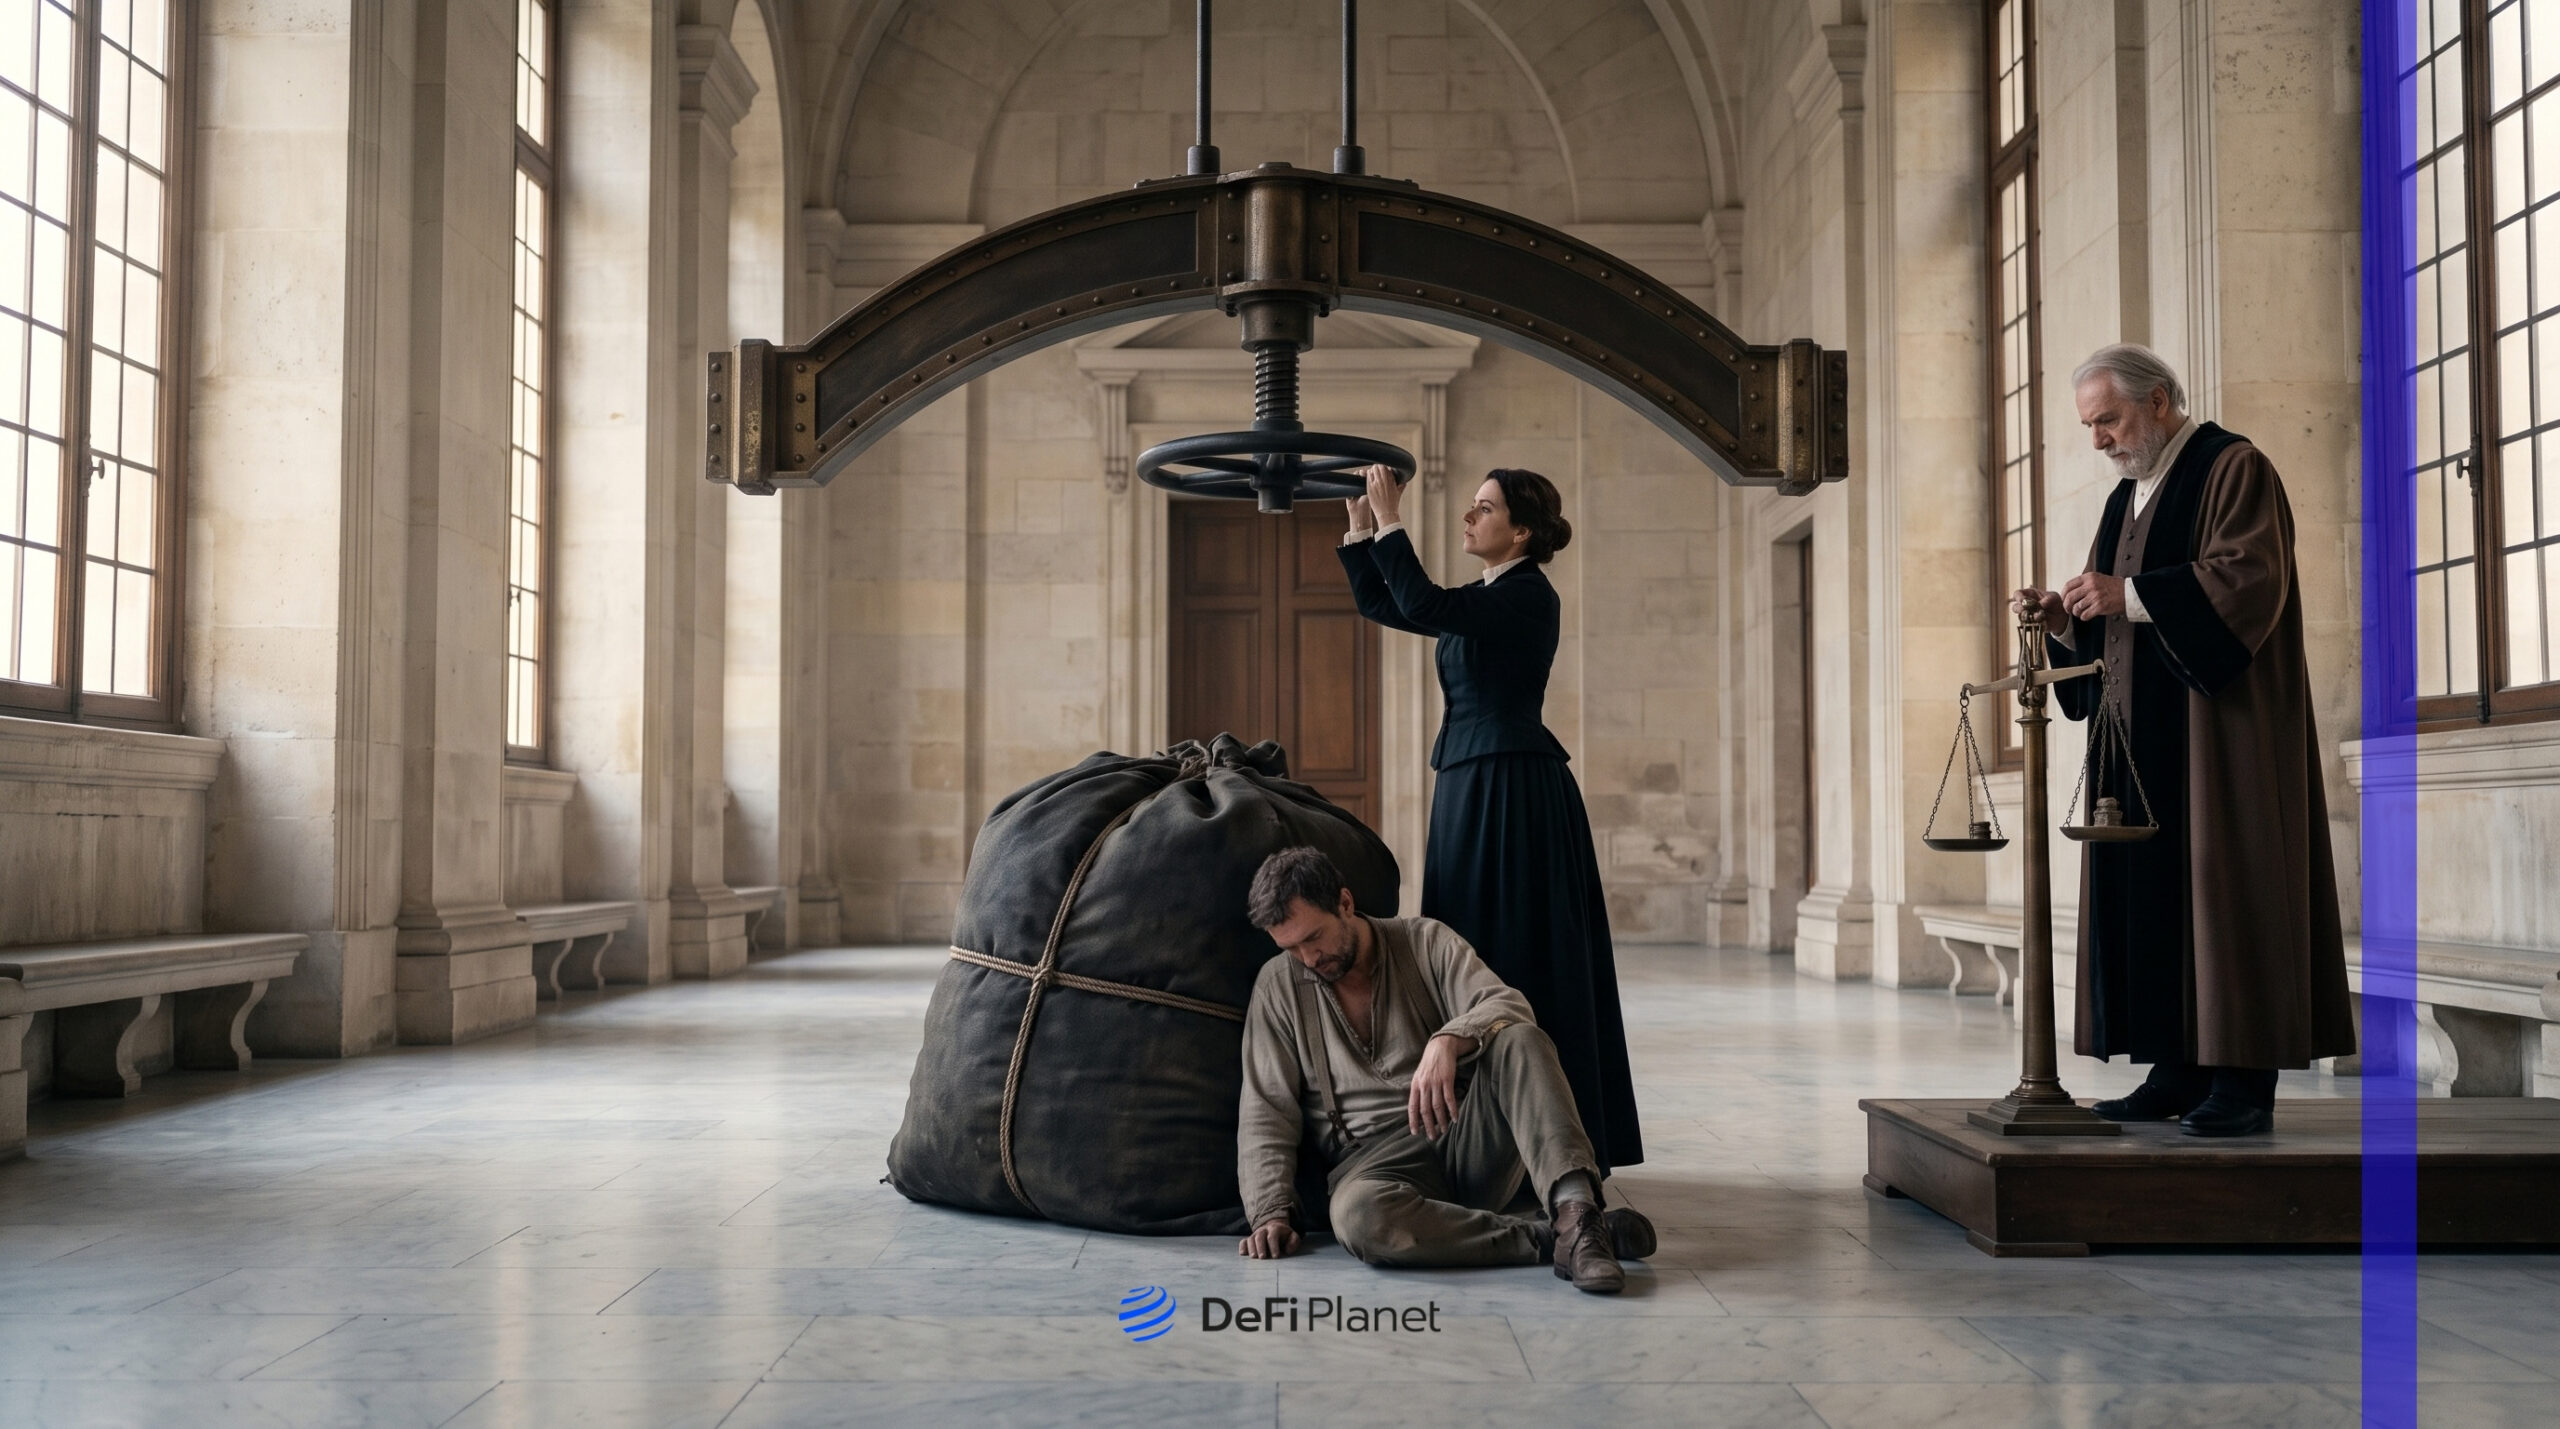
There is an old moral question that hides inside every loan agreement: Why should someone who needs money have to pay more for it simply because they need it? You might say capitalism, but mo
There is an old moral question that hides inside every loan agreement: Why should someone who needs money have to pay more for it simply because they need it?
You might say capitalism, but modern economics has a more straightforward answer: interest is the price of capital. Interest compensates for time, inflation, default risk, and the opportunity cost of lending, which might be a good enough argument in and of itself, but still, there just might exist a much better system that protects the borrower from the moral status of debt.
Aristotle of antiquity regarded making money from money as unnatural. Medieval Christian thinkers treated usury as a serious moral wrong, and Jewish and Islamic traditions developed restrictions on lending at interest, although their rules and interpretations differ across periods and communities. Islamic finance still prohibits riba, generally understood as interest, while permitting forms of trade, leasing, and risk-sharing finance. But today, most economies permit interest while regulating its extremes, and yet the ancient argument has not disappeared. It has moved into payday lending, digital credit, peer-to-peer platforms, and decentralized finance.
The interesting question, then, is not simply whether interest is morally wrong, but whether its moral status depends on the interest itself or on the economic relationship surrounding it.

The Ancient Suspicion of Making Money From Money
The history of usury begins with a conceptual problem where money is supposed to facilitate exchange, and the ethics of money came from a time when humans barely made sense of the natural world around them. In Politics, Aristotle argues that money was created to make the exchange of goods easier and that the natural purpose is therefore connected to trade and human needs, not endless accumulation.
His objection to interest follows from this idea, pointing to the Greek word tokos, which means both “interest” and “offspring.” This connects to his distinction between oikonomia, the management of a household for human needs, and chrematistike, the pursuit of wealth for its own sake. The first has a natural purpose and limit, but the second can become an endless pursuit of accumulation.

Thomas Aquinas. Source:
Mises Institute
Medieval thinkers, including Thomas Aquinas, developed related arguments arguing that lending money at interest could amount to charging twice for the same thing because money was consumed in its use, which is an argument that may sound strange to a modern economist because modern finance treats time as economically meaningful.
A dollar today is not equivalent to a dollar five years from now because capital can be invested elsewhere and inflation can reduce purchasing power. The medieval objection was not simply an error about economics, but partly an argument about justice where the lender often possessed something the borrower urgently needed. A person facing famine, illness or eviction may accept almost any available loan, creating a moral problem that may not be that capital earns a return but that one person’s vulnerability becomes another person’s opportunity for extraction.
Christianity, Islam and the Moral Meaning of Lending
The history of religious prohibitions on usury today is more complicated than saying that “religion opposed interest” because different religious traditions developed different rules, definitions, and exceptions to answer this question.
In medieval Christianity, usury was widely condemned. The Stanford Encyclopedia of Philosophy notes that the concern was partly based on the idea that a lender demanded more than was given, but Aquinas also worried that borrowers often entered such transactions out of necessity, which weakens the voluntariness of their consent.
That second argument is particularly important for modern economics in that a contract can be formally voluntary while still occurring under highly unequal conditions. Islamic finance provides a different, still-active example, with the Qur’an explicitly distinguishing trade from interest and prohibiting riba. Contemporary Islamic finance generally treats predetermined interest-bearing lending as impermissible while allowing commercial profit, leasing and structures based on risk sharing. The IMF describes the system as emphasising fairness, real economic activity, and shared risk, which is the economic philosophy behind this prohibition.
READ ALSO: Ramadan: How To Pay Zakat on Your Crypto Wealth
If a financier earns a predetermined return regardless of an investment’s outcome, the financier may transfer much of the economic risk to the borrower. Profit-sharing structures attempt to connect financial return more closely to productive activity and risk. That is not the same as saying Islamic finance has eliminated economic risk. Rather, it has chosen a different moral rule for deciding how risk and return should be distributed.
The Economics of the Cap
A 2026 NBER study of Kenya’s 2016 interest-rate regulation found that borrowers responded differently depending on their risk. The researchers found that a uniform cap could produce substantial welfare losses by eliminating credit for high-risk borrowers, while an exempt digital platform preserved some access.
Earlier World Bank researchreached a similar warning from a broader international perspective: binding caps can reduce credit supply, particularly for unsecured and small loans, while lenders may respond by shifting toward larger or safer borrowers, but the opposite argument is equally important.
Without restrictions, lenders can exploit weak competition, poor disclosure, and limited financial literacy. The World Bank notes that some lenders respond to caps by shifting costs into fees, making loans harder to compare rather than genuinely cheaper, so the choice is not simply regulated interest versus free markets, but a question of institutional design, as a poorly built cap can destroy access to credit.
DeFi Brings the Old Argument Back in New Clothing
Decentralized finance makes the question even more interesting because it removes some traditional intermediaries while preserving lending itself. Aave’s lending system lets users supply digital assets, and borrowers obtain liquidity against collateral. Interest rates respond to factors including utilization and governance parameters. When available liquidity becomes scarce, rates can rise to discourage additional borrowing and encourage additional supply.
The protocol can see collateral, utilization, and mathematical parameters, but it cannot understand that a borrower has lost a job, has a sick child or has borrowed because rent is due tomorrow. Aave founder Stani Kulechov has described the movement from its early P2P model toward pooled lending as a way to make lending more accessible and flexible because in the earlier P2P model, borrowers and lenders negotiated loan parameters directly. The pool model automated matching and allowed borrowers to access liquidity against collateral, allowing DeFi to move with some form of human discretion.
What Should Usury Laws Actually Prevent?
The history of usury suggests that societies have never been concerned only with interest rates alone. They have been concerned with exploitation, desperation, unequal bargaining power, and the social consequences of debt, which is why modern regulation reaches beyond the headline rate.
Nigeria provides a useful contemporary example: the Federal Competition and Consumer Protection Commission’s 2025 Digital, Electronic, Online and Non-Traditional Consumer Lending Regulations were introduced partly in response to complaints about abusive recovery practices, privacy violations, and exploitative behaviour in digital lending. The regulations require standards around transparency, fairness, responsible conduct, and consumer protection.
The Moral Status of Interest Is Not Settled by a Percentage
The ancient condemnation of usury and the modern defence of interest are often presented as opposites. Arguments against Aristotle and his paper still exist, based on the belief that, in the evolution of money, usury is a necessary part of economic human evolution. Ancient thinkers asked whether financial relationships could become unjust even when both parties formally agreed, but modern economists ask how capital can be allocated efficiently when lenders face risk and borrowers need funds.
The strongest lesson from the history of usury is not that interest is inherently immoral. Debt has moral consequences that cannot be captured by the interest rate alone. A lender deserves compensation for time, risk and opportunity cost, while the borrower deserves transparency and a meaningful understanding of the obligation being accepted. Neither side should be treated as merely a variable in an optimisation problem.
Interest-rate caps can protect borrowers, but badly designed caps can exclude them from formal credit, and unrestricted pricing can expand access, but also create opportunities for exploitation. P2P lending can reduce intermediary costs, but information asymmetry remains, and DeFi can automate interest rates and collateral management, but code cannot eliminate questions of justice. The enduring question behind usury laws and modern P2P lending is therefore not whether money should be allowed to make money. When does a financial return become an unfair extraction from another person’s vulnerability?
Aristotle answered that question by distrusting money making money. Medieval Christianity placed the problem inside a moral framework of justice and charity, and Islamic finance continues to reject riba while developing alternative structures based on trade, assets, and risk sharing. Modern economics still treats interest as a price that coordinates scarce capital, with the contemporary challenge being to understand where these perspectives overlap.
Maybe the most defensible lesson is not that interest is inherently good or inherently evil, but that a loan becomes morally serious when the financial price interacts with unequal power, imperfect information, and human vulnerability. The ancient word usury survives because that problem never disappeared and only the machinery changed.
Disclaimer: This article is intended solely for informational purposes and should not be considered trading or investment advice. Nothing herein should be construed as financial, legal, or tax advice. Trading or investing in cryptocurrencies carries a considerable risk of financial loss. Always conduct due diligence.
Enjoyed this? BookmarkDeFi Planet, explore related topics, and follow us onTwitter,LinkedIn,Facebook,Instagram,Threads, and CoinMarketCap Community for seamless access to high-quality industry insights.
Take control of your crypto portfolio with DEFI PLANET PRO, DeFi Planet’s suite of analytics tools.
The post Usury Laws, Interest Rate Caps, and the Moral Status of Debt appeared first on DeFi Planet.