A governance proposal on Aave to roll over USDG principal tokens in February carries a stated implied annual yield of 2.98%, but two variables complicate that figure: borrowing costs are runn
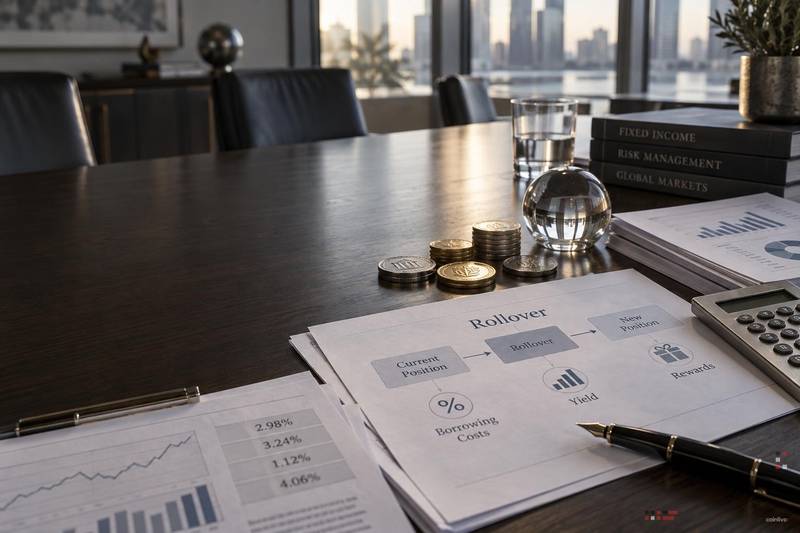
A governance proposal on Aave to roll over USDG principal tokens in February carries a stated implied annual yield of 2.98%, but two variables complicate that figure: borrowing costs are running higher, and the reward component attached to the position remains unconfirmed.
What the proposal puts on the table
The rollover targets USDG principal tokens, a fixed-maturity instrument used inside Aave's lending infrastructure. Principal tokens separate the principal and yield components of a deposit; rolling them over extends the position into a new term rather than redeeming at maturity. The proposed rollover reported by CryptoSlate prices that extension at a 2.98% implied annual yield. For related coverage, see 20,000 ETH Moved From Bitfinex to Aave: What It Means.
That figure is an implied yield, not a guaranteed return. It reflects current market pricing for the principal token rather than a locked-in payment, meaning the actual return shifts as market conditions change before and after execution. Aave has previously adjusted yield-related parameters in response to liquidity conditions, as seen when Aave raised its GHO borrow APR to 4.5% as stablecoin pools depleted. For related coverage, see SlowMist: Aave V3 Loop Safe Module Exploited, 114.09 ETH Stolen.
Borrowing costs compress the net picture
Higher borrowing costs on Aave reduce the net attractiveness of any position that requires taking on debt to fund or leverage the rollover. If a participant borrows to enter or maintain the USDG principal-token position, the spread between the 2.98% implied yield and prevailing borrow rates determines whether the trade is accretive. The proposal does not quantify the current borrowing cost delta, per available reporting.
This cost sensitivity matters most for participants using looped strategies. A similar dynamic has played out with large stablecoin inflows to the protocol; when 149.6 million USDC moved to Aave, utilisation and borrow rates shifted across affected pools.
Uncertain rewards leave the return unresolved
Beyond the base implied yield, the rollover may carry additional rewards, but those have not been confirmed in the proposal as currently reported. The distinction matters: a 2.98% implied yield is a market-derived input, while reward distributions depend on governance decisions that can change or be cancelled before the February rollover date.
Participants evaluating the proposal should track three open items before February: the final rollover terms as adopted by governance, prevailing borrow rates at the time of execution, and any formal confirmation or rejection of the reward component. A comparable Aave principal-token event, the $67.4 million in Pendle AUSD principal tokens on Aave Monad that matured October 8, illustrates how maturity and rollover mechanics interact with live market conditions.
TLDR KEYPOINTS
- 2.98% implied annual yield stated in the February USDG principal-token rollover proposal
- Higher borrowing costs on Aave reduce net yield for leveraged or looped positions
- Reward conditions unconfirmed; final return depends on governance approval before February execution
Additional source references: source document 1.
Disclaimer: This article is for informational purposes only and does not constitute financial or investment advice. Cryptocurrency and digital asset markets carry significant risk. Always do your own research before making decisions.
Read original article on coinlive.me