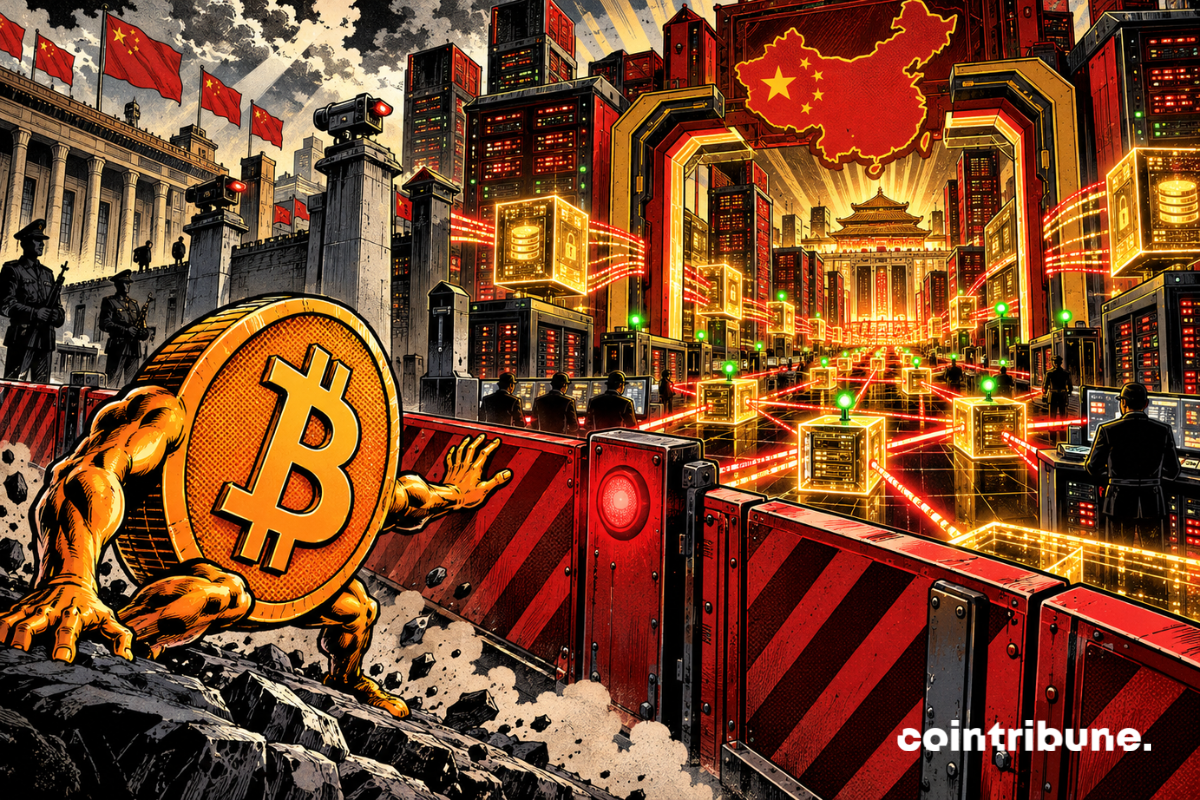
China wants to build a national blockchain network. In a strategic document published on October 9, 2026, the Central Committee of the Chinese Communist Party and the State Council list this
China wants to build a national blockchain network. In a strategic document published on October 9, 2026, the Central Committee of the Chinese Communist Party and the State Council list this infrastructure among the priorities of economic modernization. The goal is to better connect businesses, IT systems, and data nationwide. This announcement might seem favorable to Bitcoin. Yet, the official text mentions no crypto, and Beijing maintains particularly strict restrictions on their financial use.
In brief
- On October 9, 2026, Beijing officially included the construction of a national blockchain network in its economic strategy.
- The Chinese regulation of February 2026 still prohibits major trading activities and financial services related to cryptocurrencies.
- The project could strengthen Chinese digital infrastructures, but no official element demonstrates a direct benefit for Bitcoin.
China includes blockchain in its strategic infrastructures
The document published by the National Data Administration presents 19 directions aimed at developing what Beijing calls the “new productive forces.” Blockchain precisely appears at the ninth point, dedicated to the integration of the real economy and the digital economy. The government plans to build a national blockchain network alongside a unified computing network, the development of industrial artificial intelligence, and the improvement of data infrastructures.
This ambition does not arise out of nowhere. As early as 2023, Shanghai was preparing its own blockchain infrastructure, notably to facilitate data flow and modernize public services. The new plan takes a political step: blockchain is no longer considered only at the scale of certain cities or industries. It is now explicitly part of the national development directions.
The economic interest is concrete. A common infrastructure could facilitate document verification, goods traceability, and information sharing between companies and administrations.
However, the text does not specify the network budget, its deployment schedule, or its technical architecture. It is therefore a government direction, not the announcement of an already operational infrastructure.
Your 1st cryptos with BitpandaThis link uses an affiliate program.
The BSN network reveals Beijing’s true strategy
To understand this decision, one must examine an already existing infrastructure: the Blockchain-based Service Network, or BSN. Designed from 2018 with participation from the Chinese National Information Center, China Mobile, and China UnionPay, this network was publicly presented in October 2019 before its commercial launch in 2020.
In a publication dated September 20, 2026, the National Information Center describes its evolution toward digital identities, electronic certificates, and secure data exchange.
A model very different from Bitcoin.
Bitcoin operates as a public network. Anyone can verify transactions and participate in its operation according to the protocol rules, without authorization from any administration.
In contrast, a permissioned blockchain can reserve transaction validation to identified institutions. It retains shared ledger mechanisms, but its operation depends on defined governance.
The analysis of the DigiChina Stanford program notably shows that the domestic BSN was designed in an environment distinct from international public networks. This direction corresponds to the uses sought by Chinese institutions. In April 2026, Cointribune already reported the authorities’ interest in blockchain applications in banking services.
One point remains open. Indeed, the government has not indicated whether the future national network will directly rely on BSN, on a new architecture, or on several interconnected infrastructures.
Why Bitcoin remains absent from the Chinese project
The main obstacle is not technological. It is regulatory. On February 6, 2026, the People’s Bank of China and seven other authorities published a new regulation, referenced Yinfa [2026] No. 42, dedicated to the risks of cryptocurrencies and tokenization.
This official text explicitly designates Bitcoin, Ethereum, and Tether as assets without legal tender status. It prohibits in mainland China activities converting between traditional currencies and cryptocurrencies, exchanges between digital assets as well as several intermediation, financing, and marketing services associated with them.
The authorities have also strengthened restrictions on yuan-linked stablecoins and tokenized real-world assets, while providing certain exceptions for specifically authorized activities.
This policy, already analyzed by Cointribune during the tightening of stablecoin rules, shows that Beijing does not reject all distributed ledgers. It mainly seeks to prevent the development of financial systems escaping its control.
The distinction is fundamental.
A blockchain used to certify an industrial invoice does not require creating a negotiable currency on the markets. And the building of a national blockchain network does not automatically generate additional demand for bitcoin.
No provision of the October 9 plan changes the February bans. Interpreting this announcement as an upcoming legalization of bitcoin would therefore confuse a digital infrastructure policy with a financial reform.
Digital yuan and Hong Kong: two other pieces of the puzzle
The Chinese monetary strategy confirms this separation. Beijing has been developing the digital yuan, or e-CNY, for several years, a digital currency issued under the authority of the central bank. Unlike Bitcoin, this currency is not designed to operate independently of a state. It aims to modernize payments while maintaining the role of monetary institutions.
China is also seeking to expand the international use possibilities of the digital yuan. The case of Hong Kong introduces an important nuance. The special administrative region has its own regulatory framework for digital assets, different from mainland China.
But this difference does not mean that Chinese companies can freely circumvent Beijing’s restrictions. Regulatory uncertainties regarding their participation in Hong Kong’s stablecoin market had already been reported in 2025.
So, three initiatives must be distinguished: the national blockchain network for infrastructures, the digital yuan for payments, and the separately regulated digital asset market in Hong Kong. Bringing them together under a single dynamic of opening toward Bitcoin would give a misleading image of Chinese policy.
What this announcement really changes for Bitcoin
For Chinese tech companies, the decision could open new prospects in blockchain software, digital identification, traceability, and system interoperability. These prospects remain conditioned on future public investments, technical standards, and network access modalities.
For Bitcoin, the consequences are much less direct. The October 9 document foresees neither reopening of exchanges, nor authorization of new financial services in BTC, nor integration of the Bitcoin network into the announced infrastructure.
It also does not provide elements allowing a measurable effect on bitcoin’s price to be established.
Three signals will therefore deserve particular attention: the publication of a technical specification, the announcement of pilot projects with their funding, and any official modification of the February financial regulation.
Without these elements, anticipating an influx of Chinese capital towards Bitcoin would be premature. The immediate scope of the decision lies elsewhere. Beijing confirms that blockchain can become a strategic infrastructure without private cryptocurrencies obtaining a place in the national financial system. For Bitcoin, upcoming regulatory decisions, more than the construction of the network alone, will allow measuring any possible change of course.