Key Takeaways Stake growth explains roughly half the drop Falling fees and MEV explain much of the rest Solana’s decline came from shrinking issuance Real gain after dilution: about 1.7-2.2%
Key Takeaways
- Stake growth explains roughly half the drop
- Falling fees and MEV explain much of the rest
- Solana’s decline came from shrinking issuance
- Real gain after dilution: about 1.7-2.2%
Validators hold 35.9% of all ETH, the most in the network’s history, according to Bitwise’s latest staking report. The annualized yield fell from 2.81% in Q2, while Solana’s slipped from 6.38% to 5.99%.
What Bitwise reported
Bitwise reports both networks’ yields gross, before validator commission or operator fees.
Network
Supply staked, Q2 → Q3
Gross yield, Q2 → Q3
Main pressure on yield
Ethereum
33.0% → 35.9%
2.81% → 2.63%
More stake, lower fees and MEV
Solana
68% → 69%
6.38% → 5.99%
Lower issuance, slightly more stake
Source: Bitwise.
Validator counts fell on both networks, for opposite reasons. Ethereum’s dropped from about 1.1 million to 881,000 as operators merged validators under EIP-7251, which raised the maximum balance per validator to 2,048 ETH; the ETH behind those records stayed staked. On Solana, the count fell from 696 to 659 as smaller operators left under cost pressure.
Stake growth explains about half of Ethereum’s decline
Ethereum pays no fixed reward rate. Under the rules set out in its protocol documentation, the base reward per staked ETH scales with the inverse square root of all ETH staked. Total issuance rises as stake grows, but more slowly than the stake itself, so every new deposit lowers the rate paid on the rest.
Active validator balances rose 8.8% over the quarter, from 40.24 million ETH to 43.80 million. On a square-root curve, an increase of that size trims the issuance rate by roughly 3-4%, depending on whether quarter-end or average balances are used. Applied to Ethereum’s yield, that accounts for about 0.08-0.10 of the 0.18-point decline.
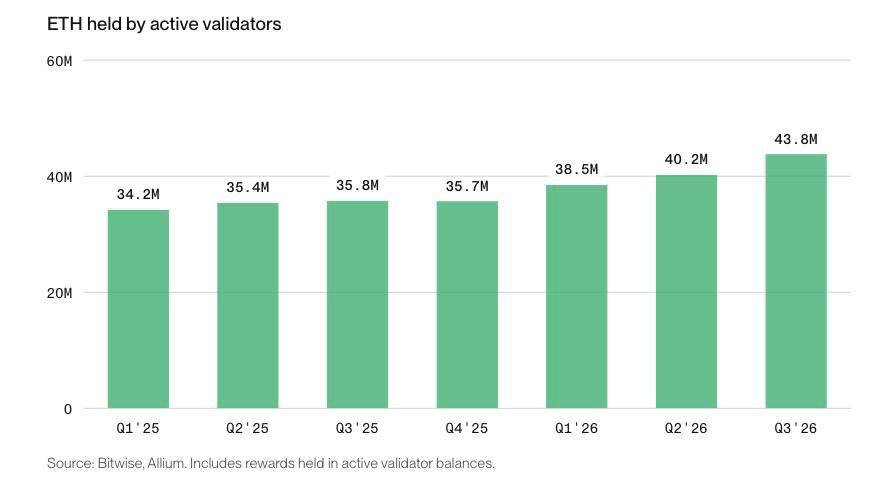
ETH held by active validators rose by 3.6 million in Q3, the biggest quarterly increase since early 2025. Source: Bitwise, Allium
The rest tracks a drop in what users paid. Network fees and MEV averaged 198 ETH a day in Q3, down 40% from 331 ETH in Q2, and part of that total is burned rather than paid to validators. Higher gas limits after the Fusaka upgrade added capacity, so users competed less for block space. Bitwise found the average cost of four common transaction types fell 67% from a year earlier.
Where Ethereum’s 2.63% came from in Q3
New issuance: 2.53 pts
Priority fees and MEV: 0.10 pts. Source: Bitwise.
Solana’s drop came from issuance, not fees
Solana’s rate moved for a different reason. Its issuance follows a disinflation schedule that currently cuts the inflation rate by 15% a year until it reaches a 1.5% floor. Issuance accounts for almost 90% of Solana’s gross staking yield, so that schedule sets the direction of rewards.
Bitwise’s breakdown shows the issuance component fell 0.53 percentage points in Q3: fewer new tokens were created, and they were spread across 3.1% more stake, now 440.5 million SOL. Fees moved the opposite way. Users paid 33% more SOL to transact, and block rewards and Jito tips added 0.14 points, leaving a net decline of 0.39 points.
What a holder actually keeps
Bitwise’s yields are measured before anyone takes a cut. A validator may charge commission, a staking pool may take a service fee, and a fund may keep part of its holdings unstaked while charging its own expenses. In an ETF, rewards often build into the value of each share instead of paying out in cash, as covered in our look at how staking rewards reach an ETF investor.
The second deduction is less visible. Most of the yield on both networks is newly created tokens, and those tokens enlarge the total supply. A staker’s share of the network therefore grows by less than the headline rate, while a holder who doesn’t stake sees their share shrink.
Rough math: yield after dilution
Ethereum
≈1.7%
Issuance paying 2.53% on 35.9% of supply adds new ETH equal to about 0.9% of total supply a year. A 2.63% yield then grows a staker’s share of all ETH by about 1.7% a year. Fee burns would lift that slightly; operator fees would reduce it.
Solana
≈2.2%
Issuance paying roughly 5.3% on 69% of supply expands total SOL by about 3.7% a year. A 5.99% gross yield then grows a staker’s share by about 2.2%, before commission. An unstaked holder’s share shrinks by about 3.5%.
Estimates from Bitwise’s Q3 figures. Results shift with stake levels, burns and commission, and exclude any change in token price.
Getting in and out
New ETH waited about 25 days to start earning at the end of Q3, down from roughly 70 days in February. Exits are capped at 57,600 ETH a day across the network, so queues can stretch when many holders leave at once; a proposed change, EIP-8061, would raise that limit to about 247,000 ETH a day by Bitwise’s estimate. Liquid staking tokens offer a faster route, because they can be sold while the underlying ETH stays staked, though a seller in a hurry may have to accept a price below the ETH they represent.
READ MORE:
 Swiss Regulator Clears First Retail Bitcoin ETF
Both networks are rethinking issuance
On Solana, faster cuts are already approved. In August, validators passed SGP-0002, which doubles the annual disinflation rate to 30% while keeping the 1.5% floor. It cleared with 67.00% support, 0.33 points above the threshold, and has no activation date yet. Once live, it would bring Solana to that floor in about 2.8 years instead of 5.7.
Ethereum’s version of the debate is less advanced. EIP-8363 would burn a rising share of consensus rewards as more ETH is staked, reaching 76% at 50 million ETH. Supporters say holders shouldn’t be diluted to fund an ever-larger security budget, while critics warn that thinner rewards would push out small operators. On September 7, the Ethereum Foundation’s protocol team declined to recommend it for the Hegotá upgrade, saying a change to issuance needs wider community discussion.
A record stake shows how much ETH and SOL is locked up. For a holder weighing staking, the figures that decide the outcome are the reward left after costs, the portion paid in new tokens and the time needed to get out.
This article is provided for informational purposes only and does not constitute financial or investment advice. Staking rewards are variable, and token-price losses can exceed rewards earned.
The post Ethereum’s Staking Record Has a Hidden Cost for Holders appeared first on Coindoo.