When a bank rejects your loan application, you tend to ask why, and if the answer says: “Your application did not meet our internal risk criteria,” that response might have been acceptable if
When a bank rejects your loan application, you tend to ask why, and if the answer says, “Your application did not meet our internal risk criteria,” that response might have been acceptable if a loan officer personally reviewed your application. It becomes much harder to defend when an artificial intelligence system analyses thousands of variables and produces the decision in milliseconds, but what exactly went wrong?
Was your income too low? Was your repayment history weak? Did your transaction behaviour raise a risk flag? Did the model use information you did not know was being considered? If the lender cannot answer those questions, the problem is bigger than poor customer service. It becomes a question of due process, fairness, and accountability.
This is why AI finance regulation has become an important aspect of finance. Financial institutions do not simply use AI to recommend products or services they offer. They use it to determine who receives credit, how much they pay for insurance, and how financial risk is assessed. The explanation is not merely a technical feature but increasingly a legal requirement and a moral expectation.
The Legal Foundations of a Right to Explanation
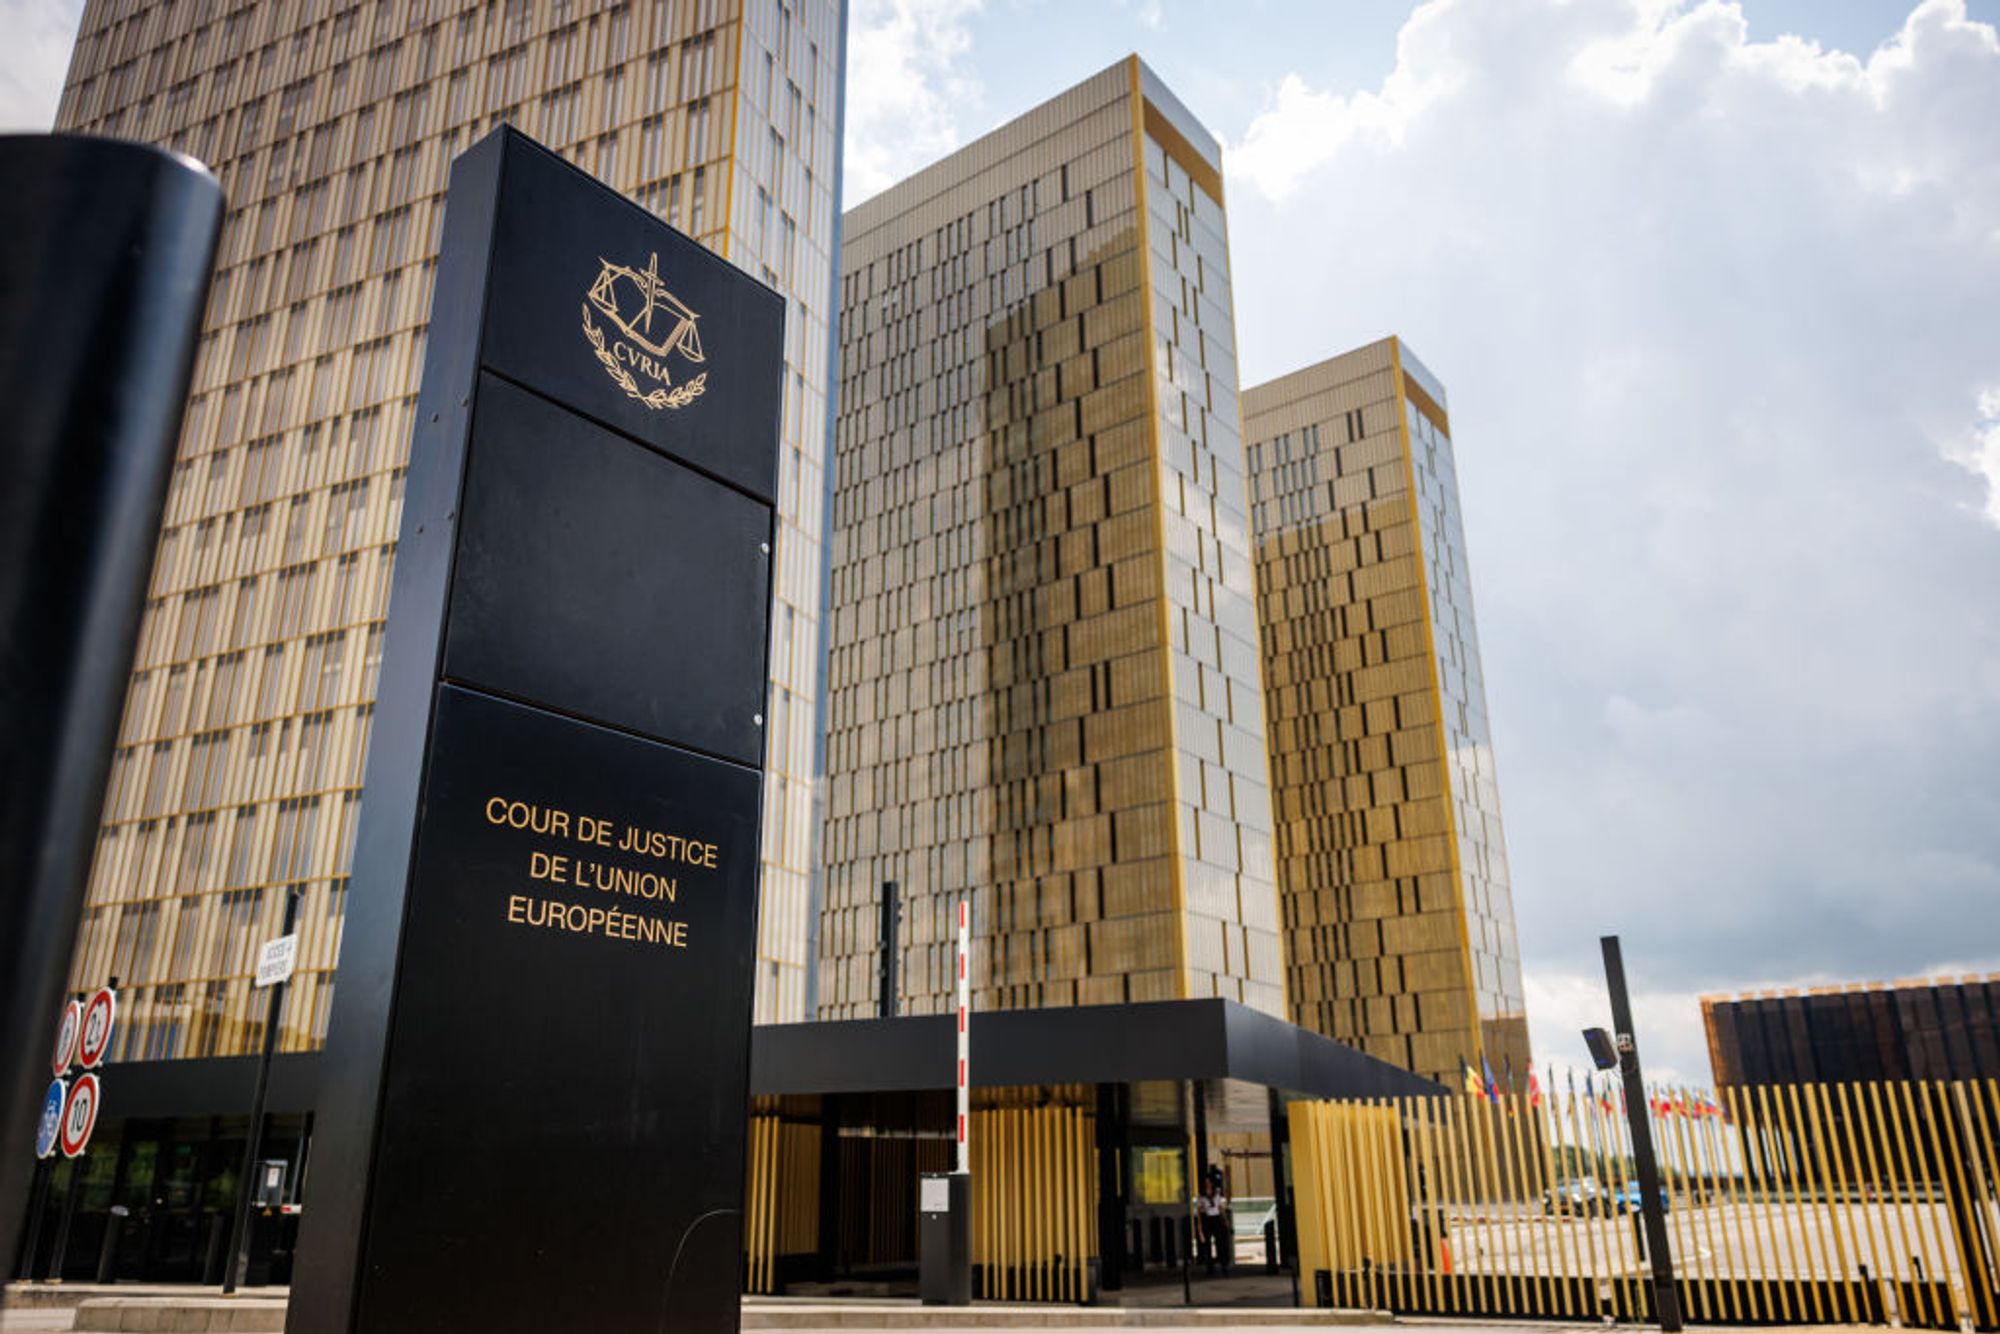
The European Court of Justice
The idea of a right to explanation for algorithmic credit is often associated with the European Union’s General Data Protection Regulation, particularly Article 22.
Article 22 restricts certain decisions based solely on automated processing where those decisions produce legal or similarly significant effects. The GDPR also provides individuals with information concerning the logic involved in certain automated decision-making processes. However, it is important not to overstate this as an unlimited right to receive the source code or every mathematical calculation behind an AI system.
The European Court of Justice gave the issue considerably more substance in its February 2025 judgment in Dun & Bradstreet Austria, which concerned an individual whose application for a mobile-phone contract was rejected following an automated assessment of her creditworthiness. The Court held that the person was entitled to an explanation sufficiently detailed to understand how the automated decision had been reached and to challenge it. The Court also made clear that providing complicated mathematical information alone would not necessarily satisfy the requirement, a distinction that matters because the law does not require a consumer to become a machine-learning engineer.
The person should be able to understand what happened to them and have a meaningful opportunity to contest it, which is a fundamentally different idea from simply making an algorithm’s code available.
Why Explanation Is About Due Process
The philosophical importance of explanation becomes clearer if we think about due process. In ordinary legal proceedings, a person affected by a decision is generally given some account of why the decision was made. A judge does not simply say, “The court has decided against you,” and end the matter. These reasons matter because they allow the person to understand the judgment, identify possible errors and, where appropriate, appeal. Financial AI creates a similar problem outside the courtroom.
A borrower may have no hearing before an automated credit decision. There may be no human conversation and no opportunity to explain an unusual circumstance, even as the decision appears on a screen.
If the system is wrong, what does the individual challenge? This is one reason transparency relates to the rule of law. A decision that cannot be meaningfully questioned becomes difficult to distinguish from an exercise of arbitrary power. The philosopher John Rawls famously treated the ability to provide public reasons as central to legitimate institutions, and jurisprudence has long linked reason-giving to accountability. AI does not eliminate that principle merely because the decision-maker is statistical, and if anything, automation makes it more important.
The Black Box Problem in Banking
This becomes particularly difficult with black box models in banking because traditional credit scoring often relies on relatively understandable variables. Black-box modelling in banking refers to using an algorithm or AI system to make financial decisions when the reasoning behind its output is difficult for humans to understand or explain. Income, debt, repayment history, and existing obligations can be explained to a customer without much difficulty, but modern machine-learning systems can operate differently, and a model may examine thousands of variables and discover complex relationships between them. Some models may also produce highly accurate predictions without offering an intuitive account of why a particular person received a particular score, creating a genuine trade-off.
A simpler model may be easier to understand but less predictive, while a complex model may identify risks that a human analyst would miss but be considerably harder to explain. The EU AI Act reflects this reasoning: AI systems used to evaluate the creditworthiness or credit score of natural persons are generally classified as high-risk because they can determine access to financial resources and essential services.

EU AI Act excerpt. Source:
AIEU
The regulation specifically recognizes the risks of discrimination and the possibility that AI systems may reproduce historical patterns of disadvantage or create new discriminatory effects.
Does a Borrower Deserve a Reason If the Model Cannot Give One?
This is perhaps the hardest question because when a bank uses an AI model that is significantly more accurate than its older scoring system, its engineers cannot produce a completely satisfying explanation for every individual prediction. But should the bank use it anyway? From a purely consequentialist perspective, there is an argument for doing so, and if the model reduces defaults and allows the bank to offer cheaper credit to more people, its overall consequences could be beneficial. A rights-based approach raises a different concern, and the individual is not merely an input into a statistical system but a person subject to a decision.
That creates what might be called a moral demand for transparency in AI finance. People should not necessarily have a right to know every internal calculation, but they should have enough information to understand the material reasons affecting their treatment.
The United States Takes a Practical Approach
The US offers a useful example because its approach focuses less on a general philosophical “right to explanation” and more on existing consumer-credit law. The Equal Credit Opportunity Act and Regulation B require creditors to provide specific reasons when taking adverse action against consumers, with the Consumer Financial Protection Bureau explicitly stating in 2023 that lenders cannot avoid this obligation simply because they use artificial intelligence or complex algorithms. If a black-box system makes it difficult to identify the actual reason for a denial, that difficulty does not excuse the lender from providing the legally required explanation.
A bank cannot simply tell a borrower: “Your application failed our internal scoring model,” because that describes the mechanism rather than the reason. The borrower needs something closer to: “Your application was declined because your existing debt obligations were too high relative to your verified income.”
The second explanation gives the person something they can understand and potentially correct and also gives the bank something to defend.
What About the UK and Emerging Markets?
The UK has taken a more principles-based route, rather than creating one sweeping AI law equivalent to the EU AI Act. UK financial regulators have been exploring how existing obligations around consumer protection, governance, accountability and model risk apply to AI.
The FCA’s research into AI-assisted credit decisions is particularly valuable because it does not assume that a theoretically explainable system automatically produces a useful explanation for ordinary people. Its experiments found that different explanations changed how effectively consumers could identify errors.
The Deeper Philosophical Problem
Modern liberal societies generally accept that power requires reasons because, as governments justify laws, courts give judgments, and regulators explain enforcement actions, administrative agencies must provide reasons for decisions affecting citizens, and such justification is not simply educational because it seeks to limit arbitrary power
Financial institutions historically occupied a different position, but they too exercise significant economic power, and an automated lending system can determine access to capital without ever speaking to the person affected. If that power becomes increasingly automated, explanation becomes one of the mechanisms through which society keeps power answerable.
This does not mean every decision must be explainable in perfect human terms, but it means that opacity should not become a substitute for accountability.
The Future of XAI in Finance
The future of financial AI will probably not be a choice between completely transparent models and completely opaque ones. It will be a question of proportionality, and the greater the consequences of an automated decision, the stronger the justification for meaningful explanation, human oversight and avenues of appeal.
The EU is moving toward explicit rights and high-risk AI obligations, while the US is applying existing credit law to increasingly complex algorithms. The UK is testing which explanations actually help consumers understand and challenge AI-assisted decisions. While these approaches differ, they converge on one principle: a financial institution cannot simply blame the machine for a consequential decision.
That may eventually be the most important idea behind explainable AI finance regulation. The purpose of XAI is not to make artificial intelligence confess every secret inside its architecture but to preserve something older than AI itself: the principle that a person affected by the exercise of power deserves a reason.
A borrower does not need to understand every parameter in a neural network, but they do need to know what counted, why it counted, whether the information was correct, and what they can do if the decision was wrong. This is where explainability becomes more than a technical preference. It becomes a condition of lawful, accountable, and morally defensible finance.
Disclaimer: This article is intended solely for informational purposes and should not be considered trading or investment advice. Nothing herein should be construed as financial, legal, or tax advice. Trading or investing in cryptocurrencies carries a considerable risk of financial loss. Always conduct due diligence.
Enjoyed this? BookmarkDeFi Planet, explore related topics, and follow us onTwitter,LinkedIn,Facebook,Instagram,Threads, and CoinMarketCap Community for seamless access to high-quality industry insights.
Take control of your crypto portfolio with DEFI PLANET PRO, DeFi Planet’s suite of analytics tools.
The post Explainable AI (XAI) as a Legal and Moral Requirement in Finance appeared first on DeFi Planet.