In brief: The GENIUS Act stablecoin rules have provided the statutory framework for payment stablecoins in the United States since July 2025, yet full implementation in the market is still ou
In brief: The GENIUS Act stablecoin rules have provided the statutory framework for payment stablecoins in the United States since July 2025, yet full implementation in the market is still outstanding. Treasury published a further proposed rule on August 17, 2026, and the OCC is aiming, by its own account, for a final rule by November 2026. January 18, 2027 counts as the central statutory date to watch, but a proposal or an expected timetable is not an applicable final rule. MiCA already gives the EU an established framework, although in legal and institutional terms it cannot be equated with the US regime.
The GENIUS Act stablecoin rules have been making headlines for months, yet many readers rightly wonder how much of it actually applies today. The answer is uncomfortable but important: the GENIUS Act was passed in July 2025, but what now shapes US stablecoin regulation are the concrete rules, procedures and supervisory decisions of Treasury, the OCC and other bodies. A statute on its own does not create a finished, workable market.
A stablecoin is at its core a crypto asset whose value is meant to be pegged to a reference, usually the US dollar. One point matters here: that stability of value is a design goal, not a guarantee. Turning a statutory framework into a functioning supervisory apparatus requires implementing rules. These are administrative provisions that translate statutory guardrails into verifiable operational requirements, covering authorisation, reserves, reporting, capital, liquidity and risk management. This article assesses neither individual tokens nor issuers and makes no statement about the specific legal compliance of USDC, USDT or any other offering.
The current legal status in one sentence
To place the debate properly, it helps to draw a clean distinction between three stages: an enacted statute, a proposed rule, and a final, applicable rule. Public Law 119-27, the official designation of the GENIUS Act, sets out the legal framework and the rulemaking mandates. Among other things it requires provisions on reserves, transparency, capital, liquidity, risk management and authorisation, yet numerous details are left for the competent agencies to pin down.
The commencement mechanism is set out precisely: the provisions apply in principle 18 months after enactment, or 120 days after final rules from the primary federal regulators, whichever comes first. As matters stand today, January 18, 2027 is the central statutory reference point, unless the alternative mechanism bites before then. That reading comes straight from the official text of the GENIUS Act as published by the U.S. Government Publishing Office.
What Treasury wants to pin down with its proposals
The US Treasury plays a central role in giving the federal framework practical shape. Its procedures are not merely communication but genuine rulemaking steps. The Treasury proposal published on August 17, 2026 is what is known as an NPRM, a Notice of Proposed Rulemaking. That means it is a draft rule, not law in final force.
In substance the draft turns on central questions of scope: when does a payment stablecoin count as issued in the United States? When is an offer or sale directed at persons in the United States? And what requirements, exemptions and safe harbors apply to foreign issuers? In its official announcement Treasury names January 18, 2027 as the expected effective date, from which payment stablecoins may in principle only be issued in the United States with a matching federal or state licence. That is a statutory expectation, not a statement that every provider is already authorised accordingly.
There is also a separate Treasury proposal from April 2026 dealing with the equivalence of state supervisory regimes. That matters because US stablecoin regulation does not run exclusively through a federal OCC licence. Subject to statutory conditions, smaller issuers with no more than 10 billion US dollars of total outstanding issuance can opt for state regulation.
In brief: The statute sets the frame, but Treasury specifies which offerings and issuers the rules practically target. The proposal of August 17, 2026 is an important implementation step, not yet the final legal position. For market watchers, what counts is the wording, the comment period, the final version and the transition periods.
Why the OCC matters for authorisation and ongoing supervision
The OCC, the Office of the Comptroller of the Currency, is the US supervisor for certain federally supervised banks and institutions. Its draft rule of March 2, 2026 is intended to pin down the requirements for issuers under OCC jurisdiction, among them federal qualified payment stablecoin issuers and certain bank subsidiaries.
The focus falls on capital and liquidity requirements, operational risk, governance and ongoing supervision. AML, CFT and OFAC sanctions obligations, by contrast, are handled in a separate, coordinated rulemaking. On the timeline: on August 19, 2026 the Comptroller stated publicly that the OCC intends to publish a final GENIUS Act rule by November 2026. That is an agency goal, not a rule already issued.
It is also worth understanding why licensing means more than a one-off approval: authorisation is followed by continuing reporting duties, examinations and supervisory processes. The OCC has already published reporting forms and instructions for this, but nothing whatsoever can be inferred from that about particular firms already being authorised.
These statements rest on the official OCC draft rule and on the OCC announcement regarding the November target.
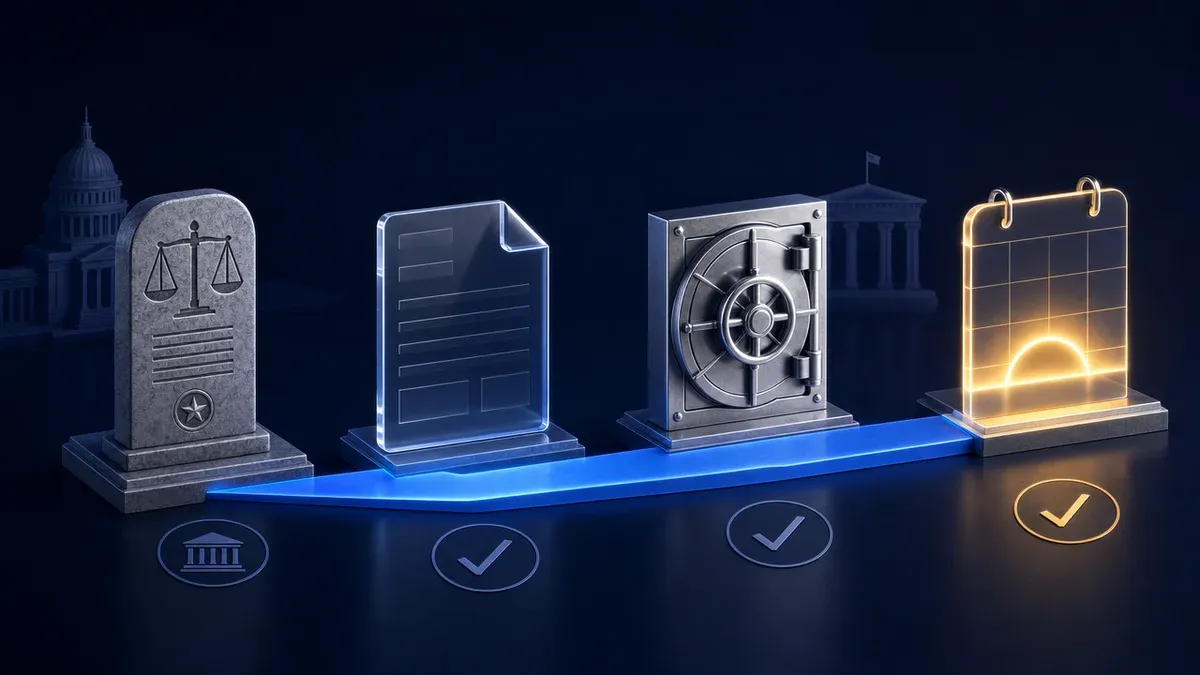
Anyone wanting to keep track can work from the following milestones:
- Already done: the GENIUS Act was passed on July 18, 2025.
- August 17, 2026: Treasury publishes a further proposal on issuance, offers and sales with a US nexus.
- Expected by November 2026: the final OCC rule, according to the Comptroller's public statement.
- January 18, 2027: the expected central statutory effective date for licensing requirements on issuance in the United States.
- July 18, 2028: a further statutory deadline for certain requirements on offers or sales by digital asset service providers.
With every fresh report, four questions pay off: is a rule merely proposed or final? Which agency has jurisdiction? Which group of actors does it cover? And what transition period actually applies? FinCEN and OFAC rules matter too: a joint proposal addresses the classification of authorised payment stablecoin issuers as financial institutions within the meaning of the Bank Secrecy Act, together with AML, CFT and sanctions obligations. That shows how individual implementation strands run in parallel.
In brief: What is decisive is the transition from legislation to application. November 2026 and January 2027 are important dates to watch, but their concrete legal effect depends on final agency publications.
What this means for well-known dollar tokens
USDC and USDT are frequently cited as examples when stablecoins come up. This article assesses neither their regulatory status nor their reserves, authorisation or the conduct of their issuers. One practical point does matter, however: neither the prominence nor the market capitalisation of a token proves that it is authorised under, or fully captured by, every US regime that may apply in future.
Three principles help with your own assessment: keep official announcements from agencies and issuers apart, do not mix up statute, draft and final rule, and do not confuse regulatory news with a statement about security, liquidity, market or counterparty risk. Stablecoins can carry market, liquidity, counterparty and technical risks despite regulatory progress. None of this is an investment recommendation.
Europe offers a reference framework with MiCA, not an identical model
In the EU, MiCA, the Markets in Crypto-Assets Regulation, already governs in detail the treatment of crypto assets not otherwise regulated, their issuers and crypto service providers. For stablecoins the relevant categories are above all asset-referenced tokens and e-money tokens, complete with authorisation, governance, transparency and supervision.
The contrast with the United States is instructive: there the statutory framework is in place with the GENIUS Act, but important operational questions are only being specified through Treasury, OCC and other rules. In the EU, MiCA is already an applicable framework, even though practical supervision is carried out by the competent national authorities. Similar aims such as transparency, reserve requirements or consumer protection do not, however, automatically mean the same token categories, licensing routes, jurisdictions or transition periods, as a look at the official MiCA text on EUR-Lex shows.
GENIUS Act stablecoin rules: the final rules are what count
As a legislative project the GENIUS Act stablecoin rules are well advanced, yet a US framework that can be relied on in practice only emerges through final Treasury, OCC and further implementing rules. Anyone following the process should keep an eye on November 2026, the expected opening of applications and above all January 18, 2027, and should base decisions exclusively on official final versions and agency guidance. This article provides general information and is no substitute for legal or investment advice.
(As of October 2, 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy.)