TLDR The fast-food giant introduced its NEXT expansion blueprint at its annual Investor Day, featuring restaurant makeovers and artificial intelligence integration. McDonald’s committed appro
TLDR
- The fast-food giant introduced its NEXT expansion blueprint at its annual Investor Day, featuring restaurant makeovers and artificial intelligence integration.
- McDonald’s committed approximately $8.5 billion in franchisee assistance extending through 2036, with $5 billion allocated by the end of this decade.
- Shares dropped 5% following the announcement and touched $234.03, marking the lowest level in almost four years.
- Domestic same-store sales dipped into negative territory during July and August, with third-quarter results projected to remain in the red.
- Wall Street firms slashed their price projections across the board, though most maintained bullish outlooks on the long-term potential.
Shares of the Golden Arches have tumbled to levels not seen since early 2021 following a negative market response to the company’s latest expansion roadmap. The stock plummeted nearly 5% last Wednesday and experienced an intraday decline of 6.5% before recovering slightly. Selling pressure continued into Thursday and Friday, bringing year-to-date losses to approximately 23%.
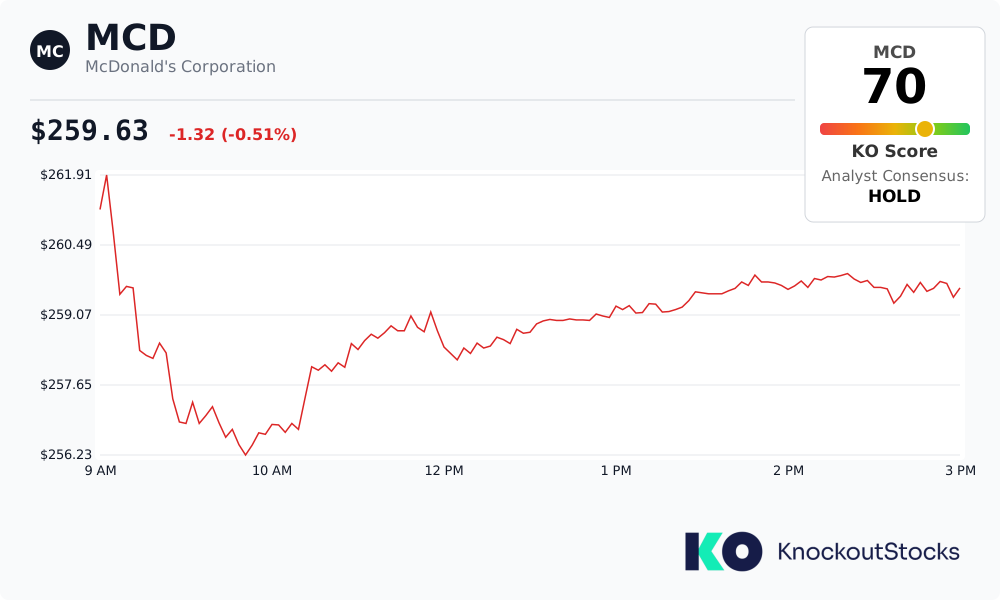 McDonald’s Corporation, MCD
The sharp decline came on the heels of the company’s Investor Day presentation, during which executives unveiled the NEXT initiative. This comprehensive program encompasses restaurant reimagining, menu enhancements, precision marketing campaigns, and artificial intelligence integration for ordering platforms and supply chain management.
The blueprint appears bold and forward-thinking. However, investors are primarily concerned not with the strategic direction, but rather with the financial commitment required and the extended timeframe for returns.
Understanding the Market Reaction
McDonald’s has committed to deploying approximately $8.5 billion in franchisee assistance over the next twelve years. The company will frontload $5 billion of this investment before 2030, including lease subsidies and $1.5 billion to $2 billion in direct capital assistance.
Company leaders project these investments will enhance restaurant-level margins by 2.5 percentage points. This translates to approximately $100,000 in additional annual operating cash per typical U.S. location.
The overarching goal: achieving an adjusted operating margin in the low-to-mid-50% territory by decade’s end. This represents a significant jump from the 47% recorded during the first six months of 2026. Reaching this milestone demands substantial upfront capital deployment, creating anxiety among shareholders focused on immediate financial performance.
Bernstein analyst Danilo Gargiulo identified the investment magnitude as the “biggest surprise” from the presentation. His calculations suggest complete implementation could require roughly $800,000 per average domestic restaurant, layered on top of standard renovation expenses.
Bank of America analysts estimate restaurants would need to generate 7% to 8% sales increases to warrant the investment, based on a 70/30 cost-sharing arrangement between franchisees and corporate. That’s a challenging benchmark considering the current operating environment.
Current Sales Momentum Remains Challenged
Customer traffic patterns are complicating the narrative. The company disclosed that domestic comparable sales posted declines throughout July and August, with third-quarter results expected to finish marginally negative despite sequential improvement during September.
Global comparable sales during the second quarter advanced just 1.3% on a year-over-year basis. This marked a deceleration from 3.8% growth in the opening quarter and 3.1% for the full 2025 calendar year. Domestic customer visits actually declined.
Raymond James analyst Brian Vaccaro noted that NEXT’s effectiveness will be evaluated “in years rather than quarters.” The company hasn’t provided specific deployment schedules for numerous components of the strategy, creating uncertainty around execution timing.
Vaccaro also highlighted a value proposition challenge. Many quick-service meals now command $10 to $13, placing McDonald’s in head-to-head competition with casual dining chains and fast-casual restaurants offering promotional pricing.
Multiple Wall Street firms adjusted their price objectives downward following the presentation. Baird reduced its target to $250 while maintaining a Neutral stance. BTIG lowered its projection to $295 but preserved its Buy recommendation. RBC trimmed to $285 with a Sector Perform designation. JPMorgan decreased to $260 while retaining an Overweight rating.
However, not all analysts adopted a pessimistic view. UBS reaffirmed its Buy recommendation and $320 price objective, emphasizing the NEXT program’s emphasis on same-restaurant sales growth and customer traffic expansion.
J.P. Morgan’s John Ivankoe suggested McDonald’s data capabilities could provide competitive advantages versus independent operators. Deutsche Bank’s Lauren Silberman expressed increasing conviction that AI-driven tools will enhance unit-level economics over the medium term.
BMO’s Andrew Strelzik characterized the margin objectives as realistic and remains positive on the valuation. He anticipates modest near-term price appreciation until the capital investments translate into measurable growth acceleration.
Over half of Wall Street analysts monitored by FactSet continue to assign Buy ratings to the stock. The consensus price target implies approximately 27% upside from current trading levels.
Bernstein maintained its Market Perform rating and $295 valuation, observing that the beverage platform introduction hasn’t generated sufficient sales momentum to counterbalance broader headwinds. The firm also noted that the enhanced chicken offering rollout timeline extends beyond initial expectations.
The post McDonald’s (MCD) Stock Plunges to 4-Year Low: Is This a Buying Opportunity? appeared first on Blockonomi.