Nexo's 2025 spending data points to higher-value purchases across travel, dining and wellness, while crypto-backed credit offers an alternative to selling digital assets. European users of th
Nexo's 2025 spending data points to higher-value purchases across travel, dining and wellness, while crypto-backed credit offers an alternative to selling digital assets.
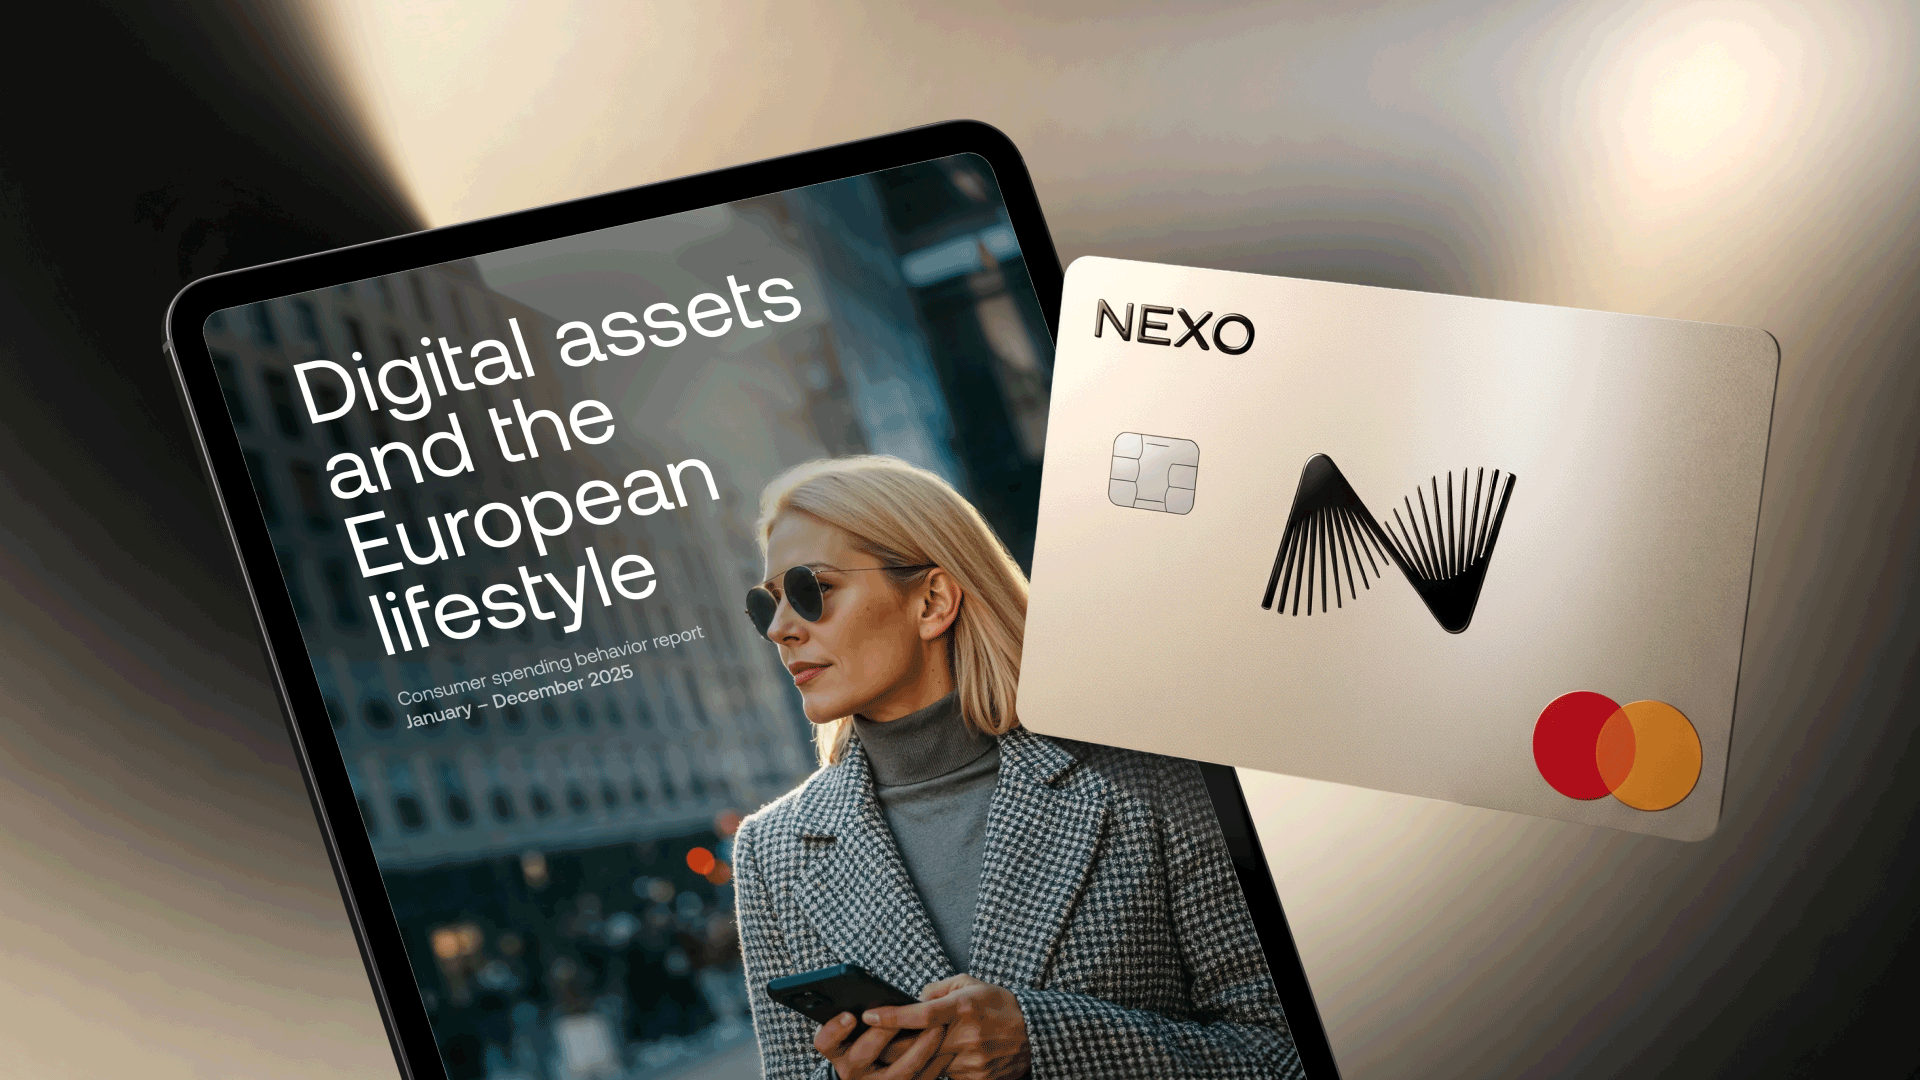
European users of the Nexo Card spent an average of approximately €80 per transaction in 2025, nearly twice the euro-area card average of €38, according to a new report from the digital asset wealth platform. The findings suggest crypto-linked payment products are increasingly being used for everyday consumption, although the data reflects Nexo's own customer base rather than the broader European payments market.
The report, titled Digital Assets and the European Lifestyle, examines spending patterns among Nexo Card users across Europe during 2025. Travel, restaurants and leisure accounted for nearly a third of spending, approximately matching combined retail spending outside groceries. Restaurants represented 88.5% of food and drink expenditure, while health and wellness spending increased 27% year over year.
Travel and entertainment also recorded 22% growth each compared with 2024, highlighting the categories where Nexo's cardholders increased spending most significantly.
The figures offer a snapshot of how digital asset holders are using payment infrastructure to access their wealth without necessarily converting their entire holdings into fiat currency.
The Nexo Card operates on Mastercard's payment network and supports both debit and credit functionality. Users can either pay directly using eligible digital assets or borrow against their crypto holdings to finance purchases.
The distinction matters for investors holding Bitcoin or Ether over longer periods. Crypto-backed credit allows them to access liquidity while retaining exposure to their assets, although borrowing introduces interest costs, collateral requirements and the risk of liquidation if asset prices decline.
Direct crypto payments offer another route. Nexo reported that stablecoins accounted for 72.7% of crypto used through its card when customers paid directly from their digital assets. Stablecoins are designed to maintain a relatively stable value, typically through a peg to a fiat currency, but their stability is not guaranteed.
The report does not establish how much of the card's overall transaction volume came from direct crypto payments versus borrowing. That distinction would help determine whether customers primarily use the product as a crypto spending wallet or as a credit facility backed by digital assets.
Travel accounted for 15.9% of Nexo Card transaction volume in 2025, making it the second-largest spending category in the report.
The timing is notable for a region where international and domestic travel remain significant consumer activities. Nexo is also extending card availability to additional European territories, including French overseas regions, Spain's Canary Islands, Ceuta and Melilla, and Finland's Åland Islands.
The expansion broadens the card's geographic reach, particularly across destinations associated with tourism. However, availability does not necessarily translate into adoption. The report does not disclose card usage or transaction growth specifically attributable to these newly covered territories.
Nexo's findings also arrive as crypto ownership expands across several European markets. The company cites early-2026 survey figures showing crypto ownership among approximately one in five respondents in the Netherlands and one in six in Germany. In France, it says 53% of crypto holders have already used digital assets to make purchases, most commonly through a card.
These figures indicate potential demand for payment infrastructure connecting digital asset holdings with conventional merchants. They do not, by themselves, establish how frequently crypto is used for payments or whether consumers prefer spending digital assets over traditional bank balances.
Nexo's transaction data provides a useful view into the behavior of customers already using a crypto-linked card, but it cannot establish broader European consumer trends.
The €80 average transaction size is particularly difficult to interpret without additional details. The report's headline comparison does not specify whether differences in customer income, transaction frequency, card usage patterns or credit utilization contribute to the gap with the euro-area average.
Nor does higher spending per transaction necessarily indicate greater overall consumption. Larger purchases could coexist with fewer transactions, while borrowing against crypto could shift the timing or funding of spending rather than increase household purchasing power.
For payment providers, the more consequential question is whether crypto-backed cards can maintain regular usage beyond travel and discretionary purchases. Grocery spending, which involved more than half of Nexo cardholders, offers one indication that the product is reaching routine consumer activity.
The broader opportunity lies in making digital asset wealth usable without requiring holders to liquidate their investments. Whether that translates into sustained payment adoption will depend on transaction costs, credit terms, merchant acceptance and consumer confidence in the underlying infrastructure.
Nexo, founded in 2018, operates a digital asset platform offering crypto-backed loans, trading, wealth management products and payment services. The company says it has processed more than $490 billion and holds over $7 billion in client assets.
The full spending report is available through Nexo's research portal : https://nexo.com/eea/research/nexo-card-report-2026