Key Takeaways Randal Konik of Jefferies maintains a Buy rating on Nike with a $75 price target, suggesting shares could more than double from current trading levels. The athletic footwear gia
Key Takeaways
- Randal Konik of Jefferies maintains a Buy rating on Nike with a $75 price target, suggesting shares could more than double from current trading levels.
- The athletic footwear giant has tumbled 44% in 2026, pressured by softening demand in China and intensified competition from brands like On Holding.
- First-quarter fiscal 2027 results are due Thursday, with Konik projecting 48 cents in EPS and $11.5 billion in revenue, topping consensus expectations.
- The upcoming November 16-17 investor day may prove more significant, particularly with incoming CFO David Denton expected to unveil updated financial projections.
- The company lost its S&P 100 membership on September 21, while Wall Street remains divided—BofA downgraded to Underperform as BTIG lifted its target.
Shares of Nike finished Friday’s session at $35.75, hovering near the 52-week bottom of $35.22. Following a devastating 44% decline throughout 2026, one Wall Street analyst believes the selloff has created an opportunity.
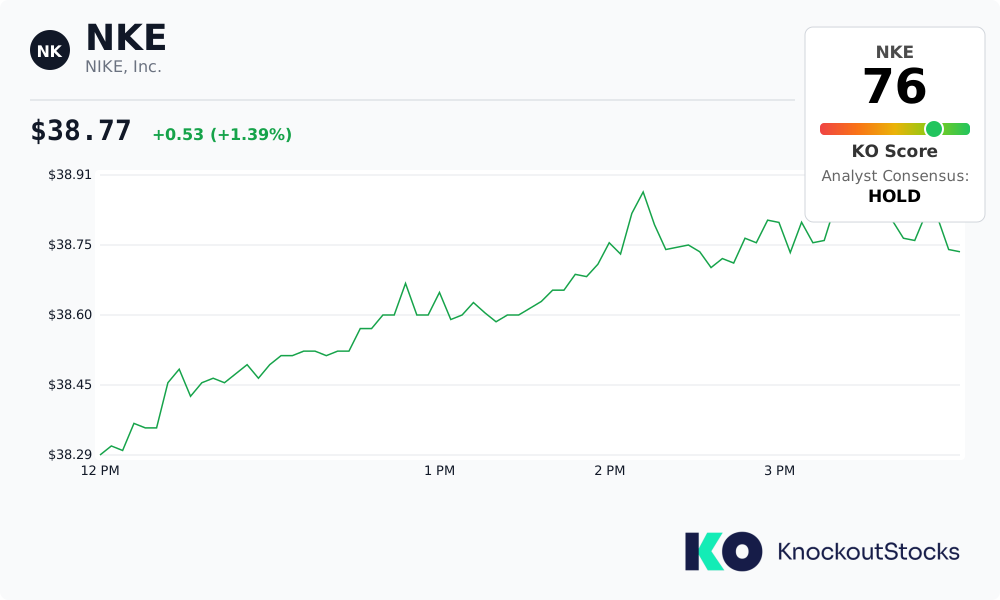 NIKE, Inc., NKE
Jefferies analyst Randal Konik reaffirmed his Buy recommendation and $75 price objective earlier this week. Should that target materialize, it would represent potential gains exceeding 100%.
Konik’s bullish stance hinges on Thursday’s quarterly financial release. He anticipates the results will demonstrate “continued progress” for the embattled athletic apparel maker.
His projections support this view. Konik forecasts 48 cents in earnings per share alongside $11.5 billion in revenue, surpassing the Street’s consensus of 44 cents and $11.3 billion.
Signs of Stabilization Emerging
Jefferies anticipates North American operations and wholesale distribution channels will stabilize during this reporting period. Enhanced inventory management should create a healthier retail environment and restore positive gross margin momentum.
Cost discipline is another expected contributor. Jefferies projects selling, general and administrative expenses declining to 34.5% of sales from 35.3%, driving EBIT margin expansion to 7.6% from 7.1%.
The company had already accelerated some gross margin improvements into this quarter. Fourth-quarter gross margin declined just 10 basis points when excluding tariff impacts, significantly outperforming management’s guidance calling for a 25 to 75 basis point contraction.
This performance stemmed from reduced promotional activity, lower reserves and fewer order cancellations in North America. These trends suggest the domestic market may be stabilizing.
However, challenges persist in certain segments. Jefferies still anticipates headwinds from Direct-to-Consumer channels, European markets and China, though profitability in these areas should bottom out before revenue recovers.
Core product categories including Classics, Sportswear and Jordan are also expected to remain under pressure. Jefferies doesn’t forecast positive growth in these lines until the latter half of fiscal 2025.
November Investor Day Takes Center Stage
Konik views Thursday’s quarterly report as merely a prelude. His primary focus is on Nike’s scheduled investor day taking place November 16-17.
Incoming CFO David Denton is anticipated to provide refreshed financial guidance during that presentation. Konik notes that a new CFO “owns none of the prior guidance,” creating an opportunity for a reset.
The critical question, according to Konik, is whether Denton establishes fiscal 2027 and 2028 targets that management can consistently achieve and exceed. Rebuilding that credibility could serve as the catalyst for sustained upward momentum.
The company’s difficult year has extended beyond stock performance. Competitor On Holding recently secured soccer superstar Kylian Mbappé’s endorsement, marking a high-profile defection from Nike.
Additionally, the company was removed from the S&P 100 index on September 21. Speculation has emerged that its inclusion in the Dow Jones Industrial Average may also be at risk.
Wall Street remains fractured in its assessment heading into the earnings announcement. BofA Securities downgraded shares to Underperform, reducing its price target to $30 while expressing concerns about innovation pipelines.
BTIG offers a contrasting perspective, elevating its price target to $55 while maintaining a Buy rating. Stifel adopted a middle position, trimming its target to $40 while reducing fiscal 2027 and 2028 earnings estimates.
BTIG forecasts first-quarter revenue of $11.4 billion, representing a 2% year-over-year decline, with adjusted earnings of 44 cents per share. Nike reports before Thursday’s opening bell.
The post Nike (NKE) Stock Could Double: Jefferies Bullish Ahead of Thursday Earnings appeared first on Blockonomi.